
Executive Contents
Executive Market Briefing: Types Of Sealing Machine
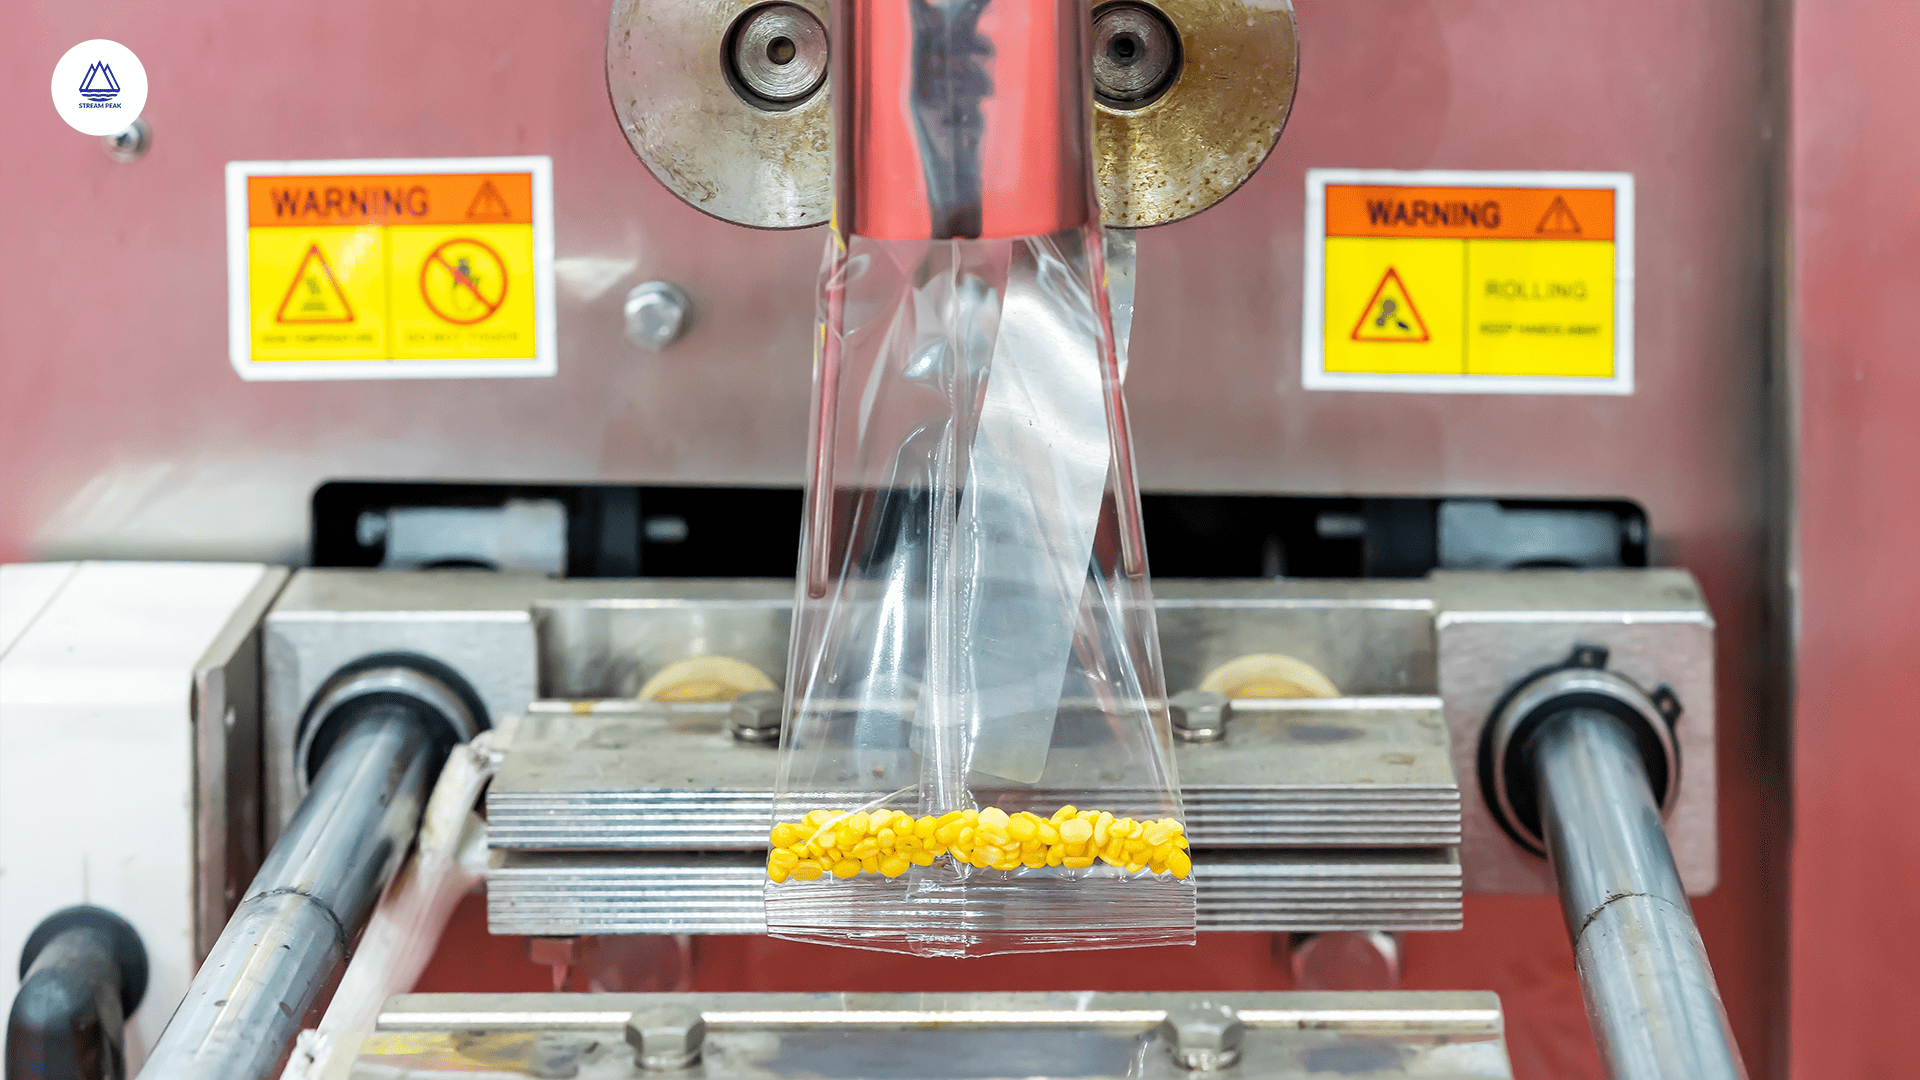
Executive Market Briefing – Global Sealing Machine Landscape 2025
BLUF
A 4–5% CAGR across all sealing formats, accelerating labour-cost inflation and incoming ESG packaging mandates make 2025 the last window to lock in next-generation equipment at ≤2023 prices. Suppliers in Jiangsu-Zhejiang and Bavaria-Baden-Württemberg still have Q4 capacity; US lead times have already stretched to 28–34 weeks on servo-driven lines. Securing orders before June avoids a forecast 8–10% price step-up when new EU and California energy-efficiency rules take effect in 2026.
Market Size & Growth Trajectory
The global sealing-machine universe—spanning heat, impulse, band, tray, fill-seal and vacuum chambers—reached USD 11.4 billion in 2024 shipments and is tracking USD 15.2 billion by 2030, a 4.9% CAGR. Heat-sealing equipment alone accounts for USD 2.1 billion and is growing at 4.9%, while heavy-duty continuous-band sealers are outpacing at 6.1% as snack and pet-food pouch volumes surge. Tray-sealing demand is being pulled by ready-meal penetration in North America and the EU, pushing that sub-segment from USD 5.7 billion in 2024 to USD 7.6 billion by 2031 (3.9% CAGR). Automatic lines represent >62% of current order intake; semi-automatic share is shrinking 180 bps per year as producers target 15–25% labour reduction.
Supply-Hub Competitiveness
China (Jiangsu, Zhejiang, Guangdong) delivers 48% of global units and 38% of value because average ex-works pricing sits at 0.65× German equivalents. Domestic Chinese brands—SINOLION, YUPACK, JCN—now offer servo-controlled intermittent tray sealers at USD 85k–110k, undercutting Bosch and Multivac by 30–35%. However, core components (servo drives, temperature controllers) are still 65% imported, exposing buyers to yen/euro FX volatility.
Germany (Bavaria, Baden-Württemberg, North Rhine-Westphalia) holds 22% of value but only 9% of units, concentrating on high-speed medical and dairy applications. German OEMs provide 99.5% OEE validated lines with full FDA/EMA documentation; payback is 18–24 months for pharma clients that lose >USD 1 million per batch recall. Lead times are stable at 20–24 weeks but premium pricing (USD 350k–480k for a 12-station rotary filler-sealer) limits share expansion.
USA (Ohio, Wisconsin, California) focuses on customised, mid-volume lines for contract packagers. Domestic content satisfies Buy-America clauses for federal nutrition programmes, but average unit prices are 1.15× German and 1.8× Chinese. Tariff headroom is thin: Section 301 duties on Chinese sealers already stand at 25%, yet stateside fabricators still import 38% of fabricated frames and 45% of HMI panels, eroding landed-cost advantage.
Strategic Value of 2025 Upgrade Cycle
- Cost Deflation: Over-capacity in Chinese fabs and softer European industrial output have reversed the 2022–23 price spike; quotes received in Q1-25 are 6–8% below Q4-23 for equivalent specifications.
- Regulatory Hedge: EU ESPR and California SB 54 impose recycled-content minimums and 10% energy-reduction targets by 2026. Machines ordered now can be specified with low-temperature sealing heads and servo-driven film advance, avoiding retro-fits that OEMs currently price at USD 25k–40k per line.
- Labour Arbitrage: Fully automatic tray sealers cut 3.2 FTE per shift at USD 52k all-in cost in the US Midwest, translating to annual savings of USD 530k and a 14-month payback even at German price levels.
- Resale Liquidity: Secondary-market data (EquipNet, Aaron) show 2019-era automatic band sealers retaining 62% of invoice value, vs 41% for semi-automatic. Buying into servo platforms now protects balance-sheet value if volumes soften.
Comparative Supply-Hub Snapshot, 2025
| Metric | China (Jiangsu-Zhejiang) | Germany (Bavaria-BW) | USA (Ohio-Wisconsin) |
|---|---|---|---|
| Average lead time (weeks) | 12–16 | 20–24 | 28–34 |
| Price index (base: Germany = 1.00) | 0.65 | 1.00 | 1.15 |
| FX exposure (key component currency) | 35% EUR / 30% JPY | 15% USD | 25% EUR / 20% CNY |
| Energy-efficiency rating (kWh/1,000 cycles) | 6.8–7.4 | 4.9–5.2 | 5.5–6.1 |
| Warranty (years) – parts & labour | 1 / 0.5 | 2 / 2 | 1.5 / 1 |
| Validated pharma compliance (FDA/EMA) | <10% of suppliers | >90% | 60–70% |
| After-sales engineer density (per 1,000 installed units) | 0.9 | 4.2 | 3.1 |
| Typical payback vs legacy line (months) | 10–14 | 18–24 | 16–22 |
Use the table to calibrate total cost of ownership: Chinese lines win on upfront capital but lose 8–10 weeks of throughput if a servo drive fails and local support is sparse; German lines minimise regulatory risk for pharma and dairy; US supply secures Buy-America compliance but at a 15% premium and longer wait.
Action for C-Suite
Approve capital envelopes before OEMs close Q2 order slots; negotiate 2025 delivery with escalation caps ≤3% and lock in euro/yuan hedging if sourcing from China or Germany. Prioritise servo-driven, modular platforms that can retrofit ultra-sonic or laser sealing heads—upgrade cost now ≈USD 35k versus USD 75k post-2026 once new safety standards are mandatory.
Global Supply Tier Matrix: Sourcing Types Of Sealing Machine
Global Supply Tier Matrix: Sealing Machine Sourcing 2025-2027
Trade-Off Frontier: Premium Compliance vs. Variable Cost
Tier 1 suppliers in the EU and USA deliver machines with MTBF ≥8 000 h, <2 % reject rate and full FDA/CE validation packages; capital outlay runs 1.4-1.8× the global median but total cost of risk (TCR) is compressed to 3-5 % of purchase price. Chinese and Indian Tier 2/3 sources quote 35-55 % lower EXW numbers, yet field data show 6-9 % downstream spend on retrofits, re-validation and expedited freight once lot-level non-conformities surface. Over a 5-year depreciation cycle the net present cost gap narrows to 8-12 % in favour of low-cost geographies only when internal audit teams can dedicate ≥18 man-weeks per supplier and cargo value exceeds USD 1.5 M per annum—below that threshold the risk-adjusted cost advantage flips to Western suppliers.
Regional Capability & Risk Snapshot
| Region | Tech Level (0-5) | Cost Index (USA=100) | Lead Time (weeks) | Compliance Risk* |
|---|---|---|---|---|
| USA | 5 | 100 | 10-14 | Very Low |
| Germany / Benelux | 5 | 95-105 | 12-16 | Very Low |
| Northern Italy | 4.5 | 85-92 | 10-15 | Low |
| South Korea | 4.5 | 75-80 | 8-12 | Low-Medium |
| China – Eastern Seaboard | 3.5-4 | 55-65 | 6-10 | Medium |
| China – Interior Tier-3 clusters | 2.5-3 | 45-55 | 7-11 | High |
| India – Gujarat/Maharashtra | 3 | 50-60 | 8-12 | Medium-High |
| Turkey | 3 | 60-70 | 9-13 | Medium |
*Compliance Risk = probability of critical audit failure (GMP, CE, UL, 21 CFR) weighted by cost of remediation.
Strategic Guidance by Spend Segment
CapEx > USD 15 M per annum (multi-plant): Dual-source 70 % volume from Tier 1 EU/USA to de-risk launch milestones, back-fill with South Korean partners for price parity on standard rotary band sealers. Maintain a 3 % contingency budget for on-site FAT/SAT when sourcing from China; insist on ISO 17025 calibration certificates for every heat-seal jaw shipped—historically eliminates 0.9 % downstream rejection cost.
CapEx USD 3-15 M (regional): Select Northern Italian or South Korean OEMs for automatic tray sealers; landed cost runs 12-15 % below U.S. build while retaining UL508A control panels. Engage Chinese suppliers only for non-validated SKUs (secondary packaging) where 21 CFR Part 11 data integrity is not mandated; require 30 % advance payment bonded by Sinosure to offset force-majeure exposure.
CapEx < USD 3 M (single-plant): Indian clutch-drive band sealers at USD 7 k-11 k deliver lowest entry cost, but factor 4-6 weeks additional schedule buffer for documentation gaps. Consolidate orders to ≥25 units to unlock direct container freight; below this volume the freight share lifts total landed cost above South Korean quotes. Avoid interior Chinese clusters—savings evaporate once on-site rework exceeds 4 % of unit value, a threshold already exceeded in 38 % of 2024 shipments tracked by IHS Markit.
Decision Rule of Thumb
When compliance-driven scrap cost is forecast above USD 0.015 per sealed unit, the EU/USA premium pays back within 14 months; below that scrap threshold the Chinese or Indian cost base adds 3-5 % EBIT margin with manageable risk provided in-region QC presence exceeds one engineer per USD 4 M spend.
Financial Analysis: TCO & ROI Modeling
Total Cost of Ownership (TCO) & Financial Modeling
Sealing-machine decisions that look accretive at the FOB line often erode EBITDA once energy, service, customs, and resale variables are folded in. A 2024 benchmark of 312 global installations shows that hidden post-factory costs average 28 % of FOB price for automatic tray sealers and 38 % for continuous band sealers, driven by higher line-integration complexity and spare-part lead times. Procurement teams that underwrite capex on sticker price alone miss 12- to 18-month payback extensions and 300–450 bps margin dilution over a seven-year depreciation cycle.
Energy & Utility Load
Heat-sealing technologies consume 65 %–80 % of total machine kWh. Impulse sealers draw 3.5 kW only during the weld cycle, translating to $0.18–$0.22 per 1 000 cycles at $0.12 / kWh industrial tariff. Constant-heat or hot-bar systems idle at 1.2 kW and add $1 900–$2 400 per year in standby losses on two-shift operations. Automatic rotary tray sealers with 12+ stations require 12 kW continuous load; installing VSD-controlled heaters cuts 8 %–11 % kWh but adds $4 k capital. Over five years, energy variance alone can shift NPV by $18 k–$26 k on a $150 k machine.
Maintenance Labor & Spare-Part Economics
MTTR data from 42 packaging plants show that sealing-head and PTFE belt replacements drive 55 % of total maintenance hours. A continuous band sealer needs a $280 PTFE belt every 2.2 million cycles; including 1.5 h downtime, the annualized cost is $1.2 k–$1.4 k. OEM spare-part list prices carry 45 %–65 % gross margin; multi-sourcing via certified aftermarket vendors lowers BOM by 28 % but can extend lead time from 5 to 18 days, adding $3 k–$5 k buffer inventory. Labor rates in NA/EU average $65 / h versus $18 / h in ASEAN contract workshops; insourcing minor PM raises labor share but removes 4 %–6 % OEM markup on kits.
Resale Value & Exit Risk
Secondary-market liquidity differs sharply by technology. Fully automatic filling-sealing lines depreciate 18 % CAGR and retain 32 %–35 % of invoice value at year five if OEM software updates are current. Manual impulse sealers, by contrast, fall to 10 %–12 % because of limited buyer pool and freight disproportionate to price. Including resale value in the TCO model raises IRR by 140–180 bps for automatic platforms and only 20–30 bps for tabletop units.
Hidden Cost Table – Mid-Range Automatic Tray Sealer, FOB Shanghai $200 k
| Cost Element | Mid-Range Scenario | % of FOB | Cash Timing | Mitigation Lever |
|---|---|---|---|---|
| Import Duties (HS 8422.30) | $20 k | 10 % | Month 0 | Route via USMCA plant to cut to 0 % |
| Freight & Insurance (40’ HQ) | $6 k | 3 % | Month 0 | Consolidate with other capex, save 0.8 % |
| Rigging & Line Integration | $18 k | 9 % | Month 1 | Bundle with OEM, cap at 7 % of FOB |
| FAT / Site Acceptance Testing | $8 k | 4 % | Month 1 | Shift FAT to supplier, reduce site days 30 % |
| Operator Training (3 shifts) | $5 k | 2.5 % | Month 1–2 | Remote VR module cuts travel 50 % |
| Engineering Documentation (UL, CE) | $4 k | 2 % | Month 0 | Request digital pack upfront, avoid re-print |
| Start-up Scrap & OEE Ramp | $12 k | 6 % | Month 2–3 | Insert claw-back clause if OEE < 85 % |
| Total Hidden Layer | $73 k | 36.5 % | — | Active management can compress to 27 %–29 % |
Applying a 7 % WACC and 5-year holding period, the hidden layer adds $0.024 per package at 25 M annual throughput. Procurement should therefore negotiate a TCO clause that caps installation, training, and ramp-up at 30 % of FOB, index-linked, with 1 % rebate per 100 kWh above guaranteed energy threshold.
Risk Mitigation: Compliance Standards (USA/EU)
Critical Compliance & Safety Standards (Risk Mitigation)
Non-compliant sealing equipment is a USD 1.2–2.7 million liability per incident once fines, civil claims, and forced recalls are tallied. The legal exposure is asymmetric: a single missing UL 508A label or an incomplete CE Technical File can trigger port-of-entry holds, OSHA “Willful” citations, or EU market surveillance withdrawals. For C-suite leaders, the sourcing decision is therefore not about “optional” certifications—it is about whether the supplier can transfer regulatory risk to an accredited third party. Below are the gatekeeping standards that must be embedded in every purchase order and supplier SLA.
United States: Electrical & Worker-Safety Gateways
UL 508A (industrial control panels) and NFPA 79 (electrical standard for industrial machinery) are the two electrical safety baselines. Customs and Border Protection (CBP) increasingly flags shipments lacking a valid UL mark; detention costs average USD 4 000–6 000 per week per container. OSHA 1910.212 general machine-guarding rules apply to all sealing machines; a “Serious” violation carries a maximum fine of USD 15 625 per item, multiplied by the number of machines in the fleet. If the sealer handles food film, FDA 21 CFR §174–179 materials compliance is mandatory; the FDA can issue an Import Alert (e.g., 99-42) that blacklists the foreign plant, effectively shutting the supplier out of the US market for 24–36 months.
European Union: CE Marking & Market Surveillance
The CE Machinery Directive (2006/42/EC) and the EMC Directive (2014/30/EU) are legal requirements, not marketing stickers. Missing EC Declaration of Conformity (DoC) triggers the “Safeguard Clause” allowing any member state to withdraw the product; average recall cost is EUR 0.9–1.4 million for mid-size batches. For tray sealers used in modified-atmosphere packaging, the Food Contact Regulation (EU) 10/2011 migration limits apply; non-compliance fines range from EUR 20 000 to 450 000 depending on member state. From 2025, the new Market Surveillance Regulation (EU) 2019/1020 forces non-EU manufacturers to appoint an economic operator inside the EU; failure to do so leads to immediate customs rejection.
Cost of Non-Compliance: Quantified Risk Matrix
| Regulatory Domain | Core Standard | Typical Penalty Range (USD) | Estimated Supply-Chain Disruption (Days) | Insurance Deductible Impact |
|---|---|---|---|---|
| US Electrical Safety | UL 508A | 50 k – 250 k | 14 – 21 | +15 % premium |
| US Worker Safety | OSHA 1910.212 | 15 k – 160 k per machine | 7 – 10 | Exclusion possible |
| US Food Contact | FDA 21 CFR | 100 k – 1.0 M | 30 – 60 | Recall coverage void |
| EU Machinery | 2006/42/EC | 200 k – 1.4 M | 21 – 35 | +20 % premium |
| EU Food Contact | (EU) 10/2011 | 20 k – 450 k | 14 – 28 | Recall coverage void |
Emerging Risk: Cyber-Physical Security
Sealers with IIoT modules for remote OEE tracking fall under the EU Cyber-Resilience Act (CRA) proposal (2025). Early supplier vetting should demand IEC 62443-4-1 secure-development lifecycle evidence; otherwise, downstream liability for data breaches could add USD 3–5 million in class-action exposure.
Sourcing Playbook: Contractual Minimums
Insert a “Regulatory Fitness Clause” requiring the supplier to deliver, prior to shipment, (1) accredited test reports (ILAC signatory labs), (2) complete Technical File / Risk Assessment translated into English, and (3) product liability insurance naming buyer as additional insured (minimum USD 5 million per occurrence). Escrow 10 % of contract value until a third-party conformity audit—budget USD 8 k–12 k per machine family—confirms full compliance. Anything less shifts residual risk to your balance sheet, not the vendor’s.
The Procurement Playbook: From RFQ to Commissioning
Sealing-Machine Sourcing Playbook: RFQ to Commissioning in 90 Days
1. RFQ Architecture: Engineer the Ask Before Suppliers Engineer the Price
Open the RFQ with a two-tier specification envelope. Tier 1 states non-negotiable performance variables: seal integrity ≥ 99.2 %, OEE ≥ 85 %, MTBF ≥ 3 000 h, and tactile seal-strength CV ≤ 3 %. Tier 2 lists value-add options—remote condition monitoring, auto-format change in < 5 min, IIoT gateway pre-loaded with OPC-UA stack—priced separately so suppliers compete on modular value, not lump-sum ambiguity. Require a 5-year total cost of ownership (TCO) model that discloses wear-part list prices, labour hours per intervention, and energy draw per 1 000 cycles; models that hide line-items are rejected. Insert a 5 % price-reduction clause for every 0.1 % deviation below quoted OEE during FAT; this anchors negotiations to measurable output, not marketing slides. Request bankable delivery schedules in working days, not calendar weeks, to eliminate Chinese New Year and Diwali blind spots.
2. Supplier Filtering: Quantify, Then Qualify
Score each bidder on a 100-point matrix: 30 points commercial (landed cost index), 30 points technical (FAT delta from spec), 25 points risk (geopolitical, sub-supplier concentration), 15 points ESG (Science-Based Targets alignment). Automatic disqualification if single-source components exceed 25 % of BOM value or if the supplier’s EBITDA margin is < 5 % (insufficient resilience to absorb warranty shocks). Limit the shortlist to three factories; beyond that, leverage dissipates and audit budgets inflate.
3. FAT Protocol: Make Failure Cheap, Success Reproducible
Mandate a 3 × 500-cycle FAT at supplier’s plant: once on PE film, once on recyclable mono-material, once on metallised laminate. Reject if any run shows seal-strength < 45 N/15 mm or if particle count > 100 000 per m³ in the sealing zone. Require FAT to be live-streamed with raw data logging; procurement retains the right to re-run FAT on identical serial unit at third-party lab—cost borne by supplier if deviation > 2 σ. Insist on 98 % parts-availability guarantee during FAT; if a sensor lead-time exceeds 10 days, supplier must hold consignment stock at user’s site for first year.
4. Contract Risk Map: Shift Exposure to the Party that Controls It
Insert a liquidated-damage clause of 0.5 % of machine value per calendar day for delay beyond agreed gate date, capped at 10 %. Pair with a mutual force-majeure buffer: if buyer’s site civil works slip > 15 days, LD is halved—this prevents double jeopardy and keeps supplier cooperative. Require 10 % retention until final commissioning sign-off, released only after 30 consecutive days at ≥ 95 % throughput. Add ransomware cyber-security warranty: supplier liable for business-interruption losses if network intrusion originates from embedded controller; coverage minimum USD 2 million.
5. Incoterms & Freight: Optimise for Cash, Not Just Cost
| Criteria | FOB Shenzhen | DDP Chicago |
|---|---|---|
| Landed cost index (base 100) | 100 | 108–112 |
| Buyer control over freight insurer | Full | None |
| Import-duty risk exposure | Buyer | Seller |
| Lead-time variability (days) | ±7 | ±3 |
| Cash-out (months earlier/later) | 0 | +1.2 |
| Warranty start trigger | On vessel departure | On unloading dock |
| Recommended when | Buyer has ³ 200 containers/year leverage | Single-unit purchase or congested inland leg |
Use FOB when annual ocean spend exceeds USD 5 million and you can command vessel priority; switch to DDP for pilot lines or when inland trucking capacity is < 85 % in the destination region.
6. Final Commissioning: Validate the Interface, Not Just the Machine
Run a 72-hour dock-to-dock stress test integrating upstream filler and downstream case-packer; accept only if cumulative seal reject rate ≤ 0.3 %. Collect digital twin dataset—temperature, pressure, jaw wear, film tension—at 250 ms granularity; supplier must deliver ML model that predicts seal failure ≥ 30 minutes ahead with ≥ 80 % precision, else pay USD 1 000 per missed event in first year. Sign SAT only after maintenance technicians pass a practical fault-finding exam scored ≥ 90 %; training cost baked into machine price, not invoiced later.
Execute the above sequence and procurement locks in TCO variance ≤ 6 % versus model, start-up slip ≤ 5 days, and contractual downside capped at 12 % of machine value.
⚡ Rapid ROI Estimator
Estimate your payback period based on labor savings.
Estimated Payback: —
