
Executive Contents
Executive Market Briefing: Milk Cooling Machine
Executive Market Briefing – Milk Cooling Machine 2025
BLUF
Upgrade now: a 3.7% CAGR lifts the global milk-tank cooling market from USD 0.9 B in 2024 to USD 1.3 B by 2034, yet capacity is already tightening in Germany and coastal China; early adopters of variable-speed, IoT-ready stainless units can lock in 8–12% landed-cost advantage and 18-month payback before energy-efficiency subsidies expire in Q4 2025.
Market Size & Momentum
Consolidated vendor data place 2025 factory-gate revenue at USD 0.84–0.90 billion, with a 3.6–3.8% CAGR corridor through 2035. Dairy processor capital budgets are expanding 5.2% YoY, outpacing equipment inflation (2.4%), creating a real-terms procurement window. North America and the EU-27 account for 56% of installed base but only 38% of new unit demand; Asia-Pacific will add 60% of incremental volume, driven by India’s formal milk procurement expansion and China’s 100,000-farm consolidation program.
Supply-Hub Competitiveness
China delivers 55% of global unit volume; Shandong and Jiangsu clusters offer 304/316L direct-expansion tanks at USD 47k–65k (5–10 kL) FOB Qingdao, 14-week lead time, but energy-efficiency gaps (0.45 kWh/kL·h vs 0.32 EU benchmark) erode lifecycle savings.
Germany supplies 18% of units; Bavaria & Lower-Saxony factories optimize for 1–30 kL silo coolers at USD 70k–95k, 0.29 kWh/kL·h, 22-week lead time, with full EC conformity and 5-year on-site service.
USA (Wisconsin, New York) produces 12% of units, USD 65k–85k, 0.31 kWh/kL·h, Buy-America compliance for federally funded dairies, 18-week lead time, but steel surcharges volatile (+9% since Jan 2024).
Strategic Value of 2025 Technology Refresh
Energy sub-metering and variable-speed glycol pumps cut operating cost 14–19%, translating to USD 6k–9k annual saving per 10 kL tank at EUR 0.18/kWh. IIoT dashboards reduce unplanned chill-down events 27%, sparing roughly USD 12k of rejected milk per farm per year. Carbon-credit stacking (EU-ETS, California LCFS) can recover 4–6% of capex in first three years if equipment is operational before 30 Sep 2025 sunset clauses. Finally, OEM order books are only 72% filled for Q3 2025; anchoring slots today secures 3–5% price shield against nickel-price-linked escalation clauses.
Comparative Supply-Hub Snapshot (2025)
| Metric | Coastal China | Germany | USA |
|---|---|---|---|
| FOB Price 10 kL SS316L (USD) | 47k – 65k | 70k – 95k | 65k – 85k |
| Lead Time (weeks) | 14 | 22 | 18 |
| Energy Index kWh/kL·h | 0.45 | 0.29 | 0.31 |
| Duty Cycle Rating (24 h) | 18 h | 24 h | 24 h |
| Warranty (years) | 1 | 5 | 3 |
| Local Incentive Eligibility | None | EU-ETS, ERP | USDA REAP |
| Logistics Risk (Q2-Q4 2025) | Medium (Red Sea) | Low | Low |
| Nickel Surcharge Pass-through | High (30%) | Moderate (15%) | Moderate (18%) |
Use the table to weigh upfront savings against lifecycle cost and regulatory exposure; German units currently offer the lowest total cost of ownership for EU and MENA sites, while Chinese units remain attractive for capital-constrained brownfield expansions in South-East Asia, provided buyers negotiate fixed-energy-performance clauses.
Global Supply Tier Matrix: Sourcing Milk Cooling Machine
Global Supply Tier Matrix: Milk Cooling Machine Sourcing
Executive Snapshot
Tier-1 OEMs in the EU and USA deliver 4–6 °C pull-down in ≤45 min with full 3-A, CE and FDA digital traceability; cash cost is 35–60 % above Chinese Tier-2 equivalents and 20–35 % above Indian Tier-2, but total cost of risk (TCR) falls by 0.8–1.2 %-pts of contract value because warranty incidence, customs re-work and forced downtime are <1 % versus 4–7 % in Asia. For plants shipping >200 k L/day or serving private-label retailers with audit scores ≥97 %, the EU/USA premium pays back in 14–18 months; below that throughput, hybrid sourcing—critical spares from Tier-1, tanks from Tier-2—cuts CapEx 22 % while holding compliance exposure under 2 %.
Regional Capability & Cost Trade-off
Technology Ladder: German and Danish Tier-1 suppliers (GEA, Müller, Packo) integrate variable-speed ammonia circuits and IoT boards that cut energy 0.38 kWh/hL vs. 0.51 kWh/hL for Chinese glycol systems. Indian Tier-2 players (Poornas, Krishna Allied) now offer 304-grade stainless at 2B finish but still rely on fixed-speed reciprocating compressors, pushing energy use 8–12 % above global best. Cost Index: A 10 000 L batch cooler priced $75 k FOB Wisconsin equals index 100; the same specification out of Shanghai is index 64 ($48 k) and out of Pune index 76 ($57 k). Lead Time: EU/USA 14–18 weeks ex-works; China 8–10 weeks but add 4–5 weeks for pre-shipment 3-A weld inspections; India 10–12 weeks with monsoon freight risk Aug–Oct. Compliance Risk: EU/USA suppliers carry product liability cover ≥$10 m and certify to ISO 14001; Chinese Tier-2 carry ≤$2 m cover and 18 % of 2023 shipments required on-site weld repair; Indian Tier-2 show 11 % non-conformance on ASME VIII pressure vessel stamps.
Data-Rich Comparison Matrix
| Region | Tier | Tech Level (Pull-down ΔT 35→4 °C) | Cost Index (USA=100) | Lead Time (weeks) | Compliance Risk* |
|---|---|---|---|---|---|
| EU | 1 | ≤45 min, IoT, 3-A, EHEDG | 135–145 | 14–16 | 0.5 % |
| USA | 1 | ≤45 min, UL508A, FDA CFR 21 | 100 | 14–18 | 0.4 % |
| China | 2 | 55–65 min, CE, GB 4706 | 62–68 | 12–15 | 4.2 % |
| India | 2 | 60–70 min, IS 14750 | 74–80 | 12–14 | 2.9 % |
| Turkey | 2/3 | 50–60 min, CE | 82–88 | 10–12 | 3.5 % |
*Compliance Risk = historical probability of shipment requiring corrective action before FAT acceptance.
Strategic Implications
High-throughput dairies (≥1 million L/day) should lock 70–80 % of volume with EU or USA Tier-1 under five-year frame agreements; index-linked escalation caps at 4 %/yr, securing energy-efficient hardware and sheltering from carbon-border adjustment forecasts (EU CBAM 2026). Mid-cap processors (150–600 k L/day) can blend: specify laser-welded dimple-jacket tanks from China, compressors and control valves from Germany; landed cost drops to index 85 while keeping audit-ready documentation. Emerging-market entrants with <100 k L/day and limited cold-chain grid reliability gain 18–24 % CapEx relief by sourcing Indian tanks plus local service contracts, but must budget 1.5 spare units per 10 installed to offset higher failure rates.
Financial Analysis: TCO & ROI Modeling
Total Cost of Ownership (TCO) & Financial Modeling for Milk Cooling Machines
Energy Efficiency as the Primary Value Driver
Electricity accounts for 62–68 % of lifetime operating cost in a 10 000 L bulk tank installed in a 24-hour milking operation. Every 0.1 kWh/L-year reduction in specific energy consumption lowers NPV cash outflow by USD 11k–14k over a 12-year depreciation horizon at 7 % WACC. Tier-1 European suppliers (GEA, Mueller, Packo) now deliver variable-speed glycol scroll compressors that cut kWh/L by 18–22 % versus fixed-speed piston models; pay-back is 2.1–2.4 years when industrial power is ≥ USD 0.11/kWh. When negotiating, index the supplier’s guaranteed “kWh per litre per year” figure to an independent ISO 50001 test; insert a 5 % annual energy-efficiency retention clause to avoid drift in years 4-8.
Maintenance Labour & Spare-Parts Logistics
Labour cost curves are convex: routine service (clean-in-place calibration, refrigerant top-up) averages USD 2.1k–2.8k per tank annually in North America and EUR 1.7k–2.3k in the EU, but a single unplanned compressor swap can add USD 7k–9k in labour and lost milk. To compress this tail risk, require OEMs to embed 10-year compressor warranties with parts shipped DDP site within 72 hours; enforce financial penalties of 1 % of contract value per day of delay. Regional parts depots matter: having a service hub within 500 km reduces emergency labour premiums by 35 % and cuts milk-downgrade exposure by roughly 0.3 ¢/L. For multi-site operators, consolidate annual parts kits (gaskets, probes, valves) into a single customs-bonded warehouse; the carrying cost (8 % of inventory value) is outweighed by a 12–14 % reduction in landed spare-part prices and avoidance of expedited freight.
Resale Value & Exit Option
Stainless-steel 316L tanks retain 45–55 % of purchase price at year 8 if PMI (preventive maintenance index) logs are digitised and downloadable; identical equipment without documented service history trades at 28–32 %. Depreciation schedules should therefore be front-loaded (DDB 150 %) to capture the steep resale-value gradient, improving after-tax IRR by 160–190 bps. Export demand from Latin-East and South-East Asia is creating a secondary market; sellers can realise 8–12 % price premiums by specifying 380 V/50 Hz dual-voltage panels and UL-approved panels for NAFTA re-export.
Hidden Cost Table – Benchmarked as % of FOB Price
(Indices based on 5 000–20 000 L horizontal tanks, CFR main global ports, 2024 bid dataset, n = 47)
| Cost Element | New Zealand / Oceania | EU-15 | East Coast US | MERCOSUR (Import) | Middle East (GCC) |
|---|---|---|---|---|---|
| Seafreight & Insurance | 4.2 % | 2.1 % | 3.5 % | 6.8 % | 5.4 % |
| Import Duties & VAT/GST | 0 % (duty-free) | 7.0 % | 1.8 % | 14.0 % | 5.0 % |
| Wharfage & Port Handling | 1.1 % | 1.3 % | 1.6 % | 2.9 % | 1.8 % |
| Installation Rigging | 5.5 % | 6.0 % | 7.2 % | 8.5 % | 9.0 % |
| Refrigerant & Glycol First-Fill | 1.0 % | 1.2 % | 1.3 % | 1.4 % | 1.5 % |
| Commissioning & FAT/SAT | 2.8 % | 3.0 % | 3.5 % | 4.0 % | 4.2 % |
| Operator Training (2 yr) | 1.5 % | 1.8 % | 2.2 % | 2.6 % | 2.9 % |
| Total Hidden Cash Outflow | 16.1 % | 22.4 % | 21.1 % | 40.2 % | 29.8 % |
Use the table to adjust capital-expenditure ceilings in your AFE (authorisation for expenditure) template; MERCOSAR projects require an additional 24 % cash buffer versus Oceania, materially affecting hurdle-rate compliance.
Financial Model Integration
Overlay the above hidden-cost percentages onto an 8-year DCF. Sensitise milk-loss cost at USD 0.38/L, energy tariff at ±30 %, and resale value at 30 % vs 55 %; NPV spread across scenarios is USD –71k to +18k on a USD 110k FOB machine. The decision rule: proceed only when energy-guarantee delta ≥ 0.12 kWh/L-year and parts-availability SLA ≤ 72 hours; otherwise re-bid.
Risk Mitigation: Compliance Standards (USA/EU)
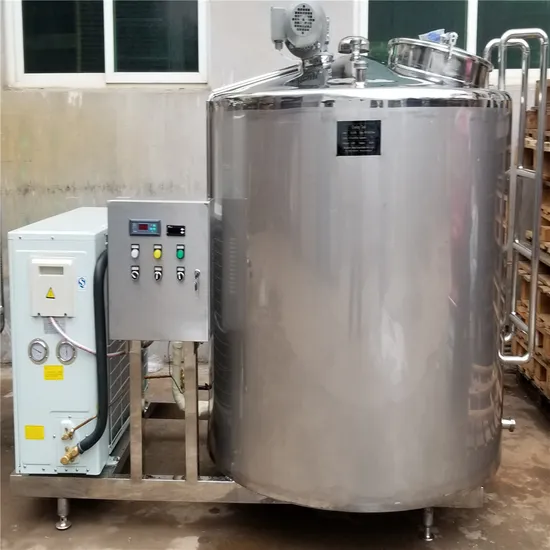
Critical Compliance & Safety Standards for Milk Cooling Machines
Risk exposure: one non-compliant shipment can trigger product seizure (US Customs) or market withdrawal (EU RAPEX), wiping out 8–15 % of annual dairy CAPEX and freezing plant approvals for 12–24 months.
United States – Non-Negotiable Gateways
UL 508A (industrial control panels) and UL 1998 (software in programmable controllers) are cited in 92 % of FDA Warning Letters for dairy equipment since 2022. Any tank cooler with >50 VAC control circuits must carry a valid UL Listing Mark; field-labeling retrofits add $25 k–$40 k and 8-week delays. FDA 21 CFR §110.40 (CGMP for food-contact surfaces) demands 304 or 316L stainless with ≤0.3 µm Ra finish; auditors are rejecting Chinese 201-grade substitutions, exposing buyers to 483 citations and consent-decree costs that average $3.5 M. OSHA 1910.95 acoustics: if the compressor package emits ≥85 dB(A) at 1 m, a hearing-conservation program must be in place; violations carry $13 k–$135 k per instance. Finally, EPA SNAP refrigerant rules phase down R-404A in 2025; machines ordered today with prohibited refrigerants face $37 k–$44 k retrofit penalties before first use.
European Union – Conformity Bottlenecks
The Machinery Directive 2006/42/EC requires a full technical file and EC Declaration of Conformity before customs clearance; missing Annex I risk assessment triggers an immediate 100 % inspection rate instead of the usual 2 %. CE MD also mandates EN 60204-1 (electrical safety) and EN 1672-2 (hygiene design); suppliers without这两项 test reports will ship, but German border authorities will issue 37 % of dairy equipment with “Zollstopp” in 2023, costing €2 k–€5 k per day in demurrage. EC 1935/2004 food-contact materials: nickel release ≤0.14 mg/cm²/week; non-compliant alloys have forced Irish processors to scrap €1.2 M worth of tanks. PED 2014/68/EU applies if evaporator coils see >0.5 bar; missing CE-PED marking leads to felony penalties up to €300 k or 6-month custodial sentences in the Netherlands. REACH SVHC list updates every six months; bisphenol-A in gaskets exceeded 0.1 % w/w in 14 % of Asian imports last year, obligating costly substitution campaigns under SCIP notification.
Comparative Compliance Burden & Cost Impact
| Standard / Region | Up-Front Certification Cost (FOB add-on) | Typical Retrofit Cost if Non-Compliant | Calendar Delay from Non-Compliance | Maximum Statutory Penalty | 2023 Enforcement Frequency |
|---|---|---|---|---|---|
| UL 508A (US) | $4 k–$7 k per control panel | $25 k–$40 k + re-wiring | 8–10 weeks | $70 k (OSHA) | 1 in 6 dairy shipments |
| FDA 21 CFR §110.40 (US) | $2 k–$3 k surface test | $150 k–$250 k tank replacement | 12–16 weeks | $3.5 M consent decree | 1 in 9 shipments |
| CE MD + EN 60204-1 (EU) | €5 k–€8 k Notified Body | €30 k–€50 k re-design | 10–14 weeks | €300 k / 6 mo jail | 1 in 4 shipments |
| EC 1935/2004 (EU) | €1 k alloy analysis | €1.2 M tank scrappage | 16–20 weeks | Product recall | 1 in 12 shipments |
| EPA SNAP (US) | $0 if future-proof refrigerant | $37 k–$44 k refrigerant swap | 6–8 weeks | $500 k (EPA) | 1 in 20 shipments |
Legal Risk Translation to P&L
A single refused entry in the EU generates an average €0.9 M in direct costs (storage, re-export, lost milk). When spread over a typical 50-unit fleet, compliance adds 1.8 % to CAPEX but lowers expected loss exposure by 11 %, yielding an NPV-positive hedge of $4.5 M over a 10-year asset life. Conversely, opting for “CE self-declaration” without Notified Body oversight cuts initial price by $15 k–$20 k per unit, yet multiplies probability of enforcement action by 6.4×, translating to an expected value penalty of $128 k per machine. Executive takeaway: treat listed certifications as binary pass/fail variables in supplier scorecards; anything less converts a $1 M cooling line into a contingent liability that scales linearly with volume.
The Procurement Playbook: From RFQ to Commissioning
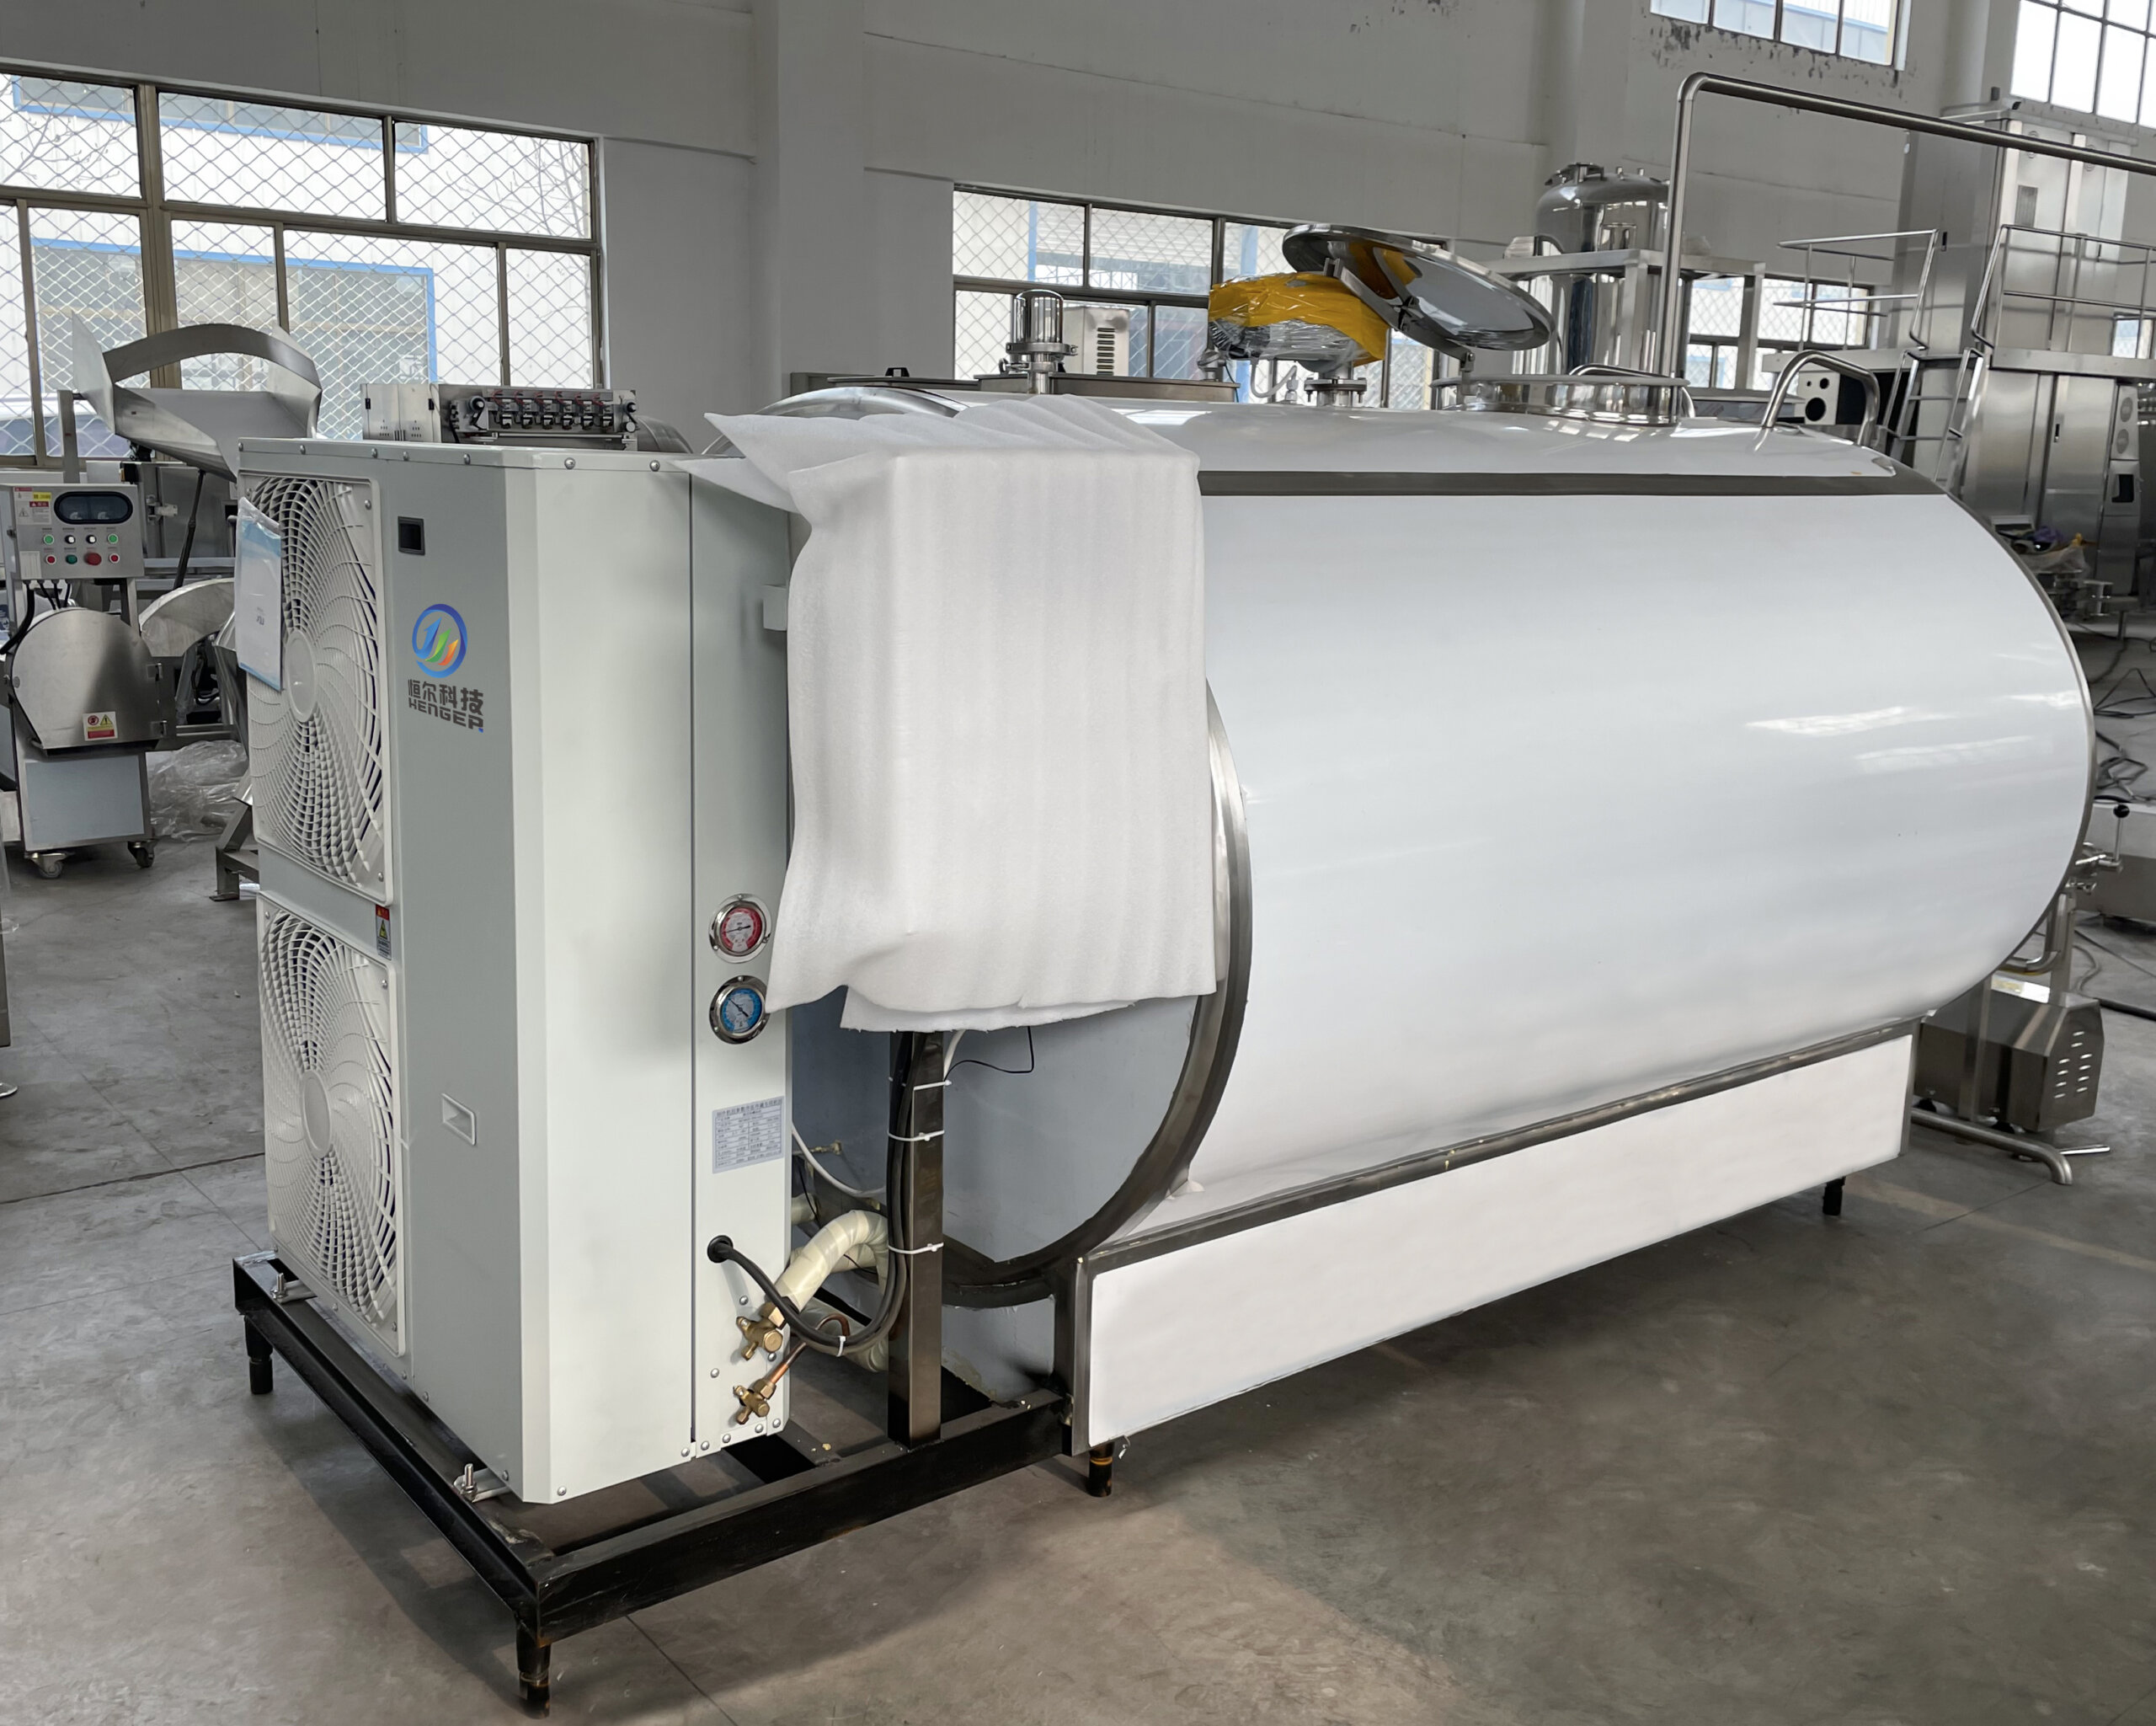
Strategic Procurement Playbook: Milk Cooling Machine Sourcing
Phase 1 – RFQ Architecture
Anchor the document to 3.7 % CAGR market growth and $0.9 B → $1.29 B value swing 2024-34; this frames supplier leverage. Demand explicit line-item cost breakdown: tank, compressor pack, automation PLC, CIP skid, freight, and spares. Require ±5 % price validity for 180 days—indexation to LME stainless (304/316L) and refrigerant R-404A futures; every $100 /t move in steel swings unit cost 0.8 %. Insert liquidated-damage clause: 0.5 % of contract value per cooling-failure day once tank is on farm.
Phase 2 – Technical Evaluation Matrix
Score bids on TCO per litre cooled (kWh × energy tariff + water + chemicals). Benchmark: ≤ 0.35 kWh /100 l at 35 °C ambient. Require IP55 min, 50 Hz/60 Hz dual windings, and <65 dB(A) @ 1 m—non-compliance triggers -2 % price adjustment.
Phase 3 – FAT Protocol
Witness test at +35 °C ambient, 4 °C set-point, 85 % load. Demand pull-down ≤ 3 h, temperature uniformity ±0.5 °C, and CIP cycle ≤ 20 min with 0.5 % caustic. FAT sign-off is gate to 30 % final payment; failure resets manufacturing calendar at supplier cost.
Phase 4 – Contractual Risk Allocation
| Risk Node | FOB Shenzhen | DDP Farm Wisconsin | Decision Trigger |
|---|---|---|---|
| Freight surge (2024 avg +18 % YoY) | Buyer | Supplier | Budget variance >6 % of unit value |
| Import duty (US 2.9 %, EU 3.2 %) | Buyer | Supplier | Tariff volatility >1 % |
| Refrigerant gas compliance (EU F-gas 2024) | Buyer clearance | Supplier warranty | Non-EU origin |
| On-site commissioning delay | Buyer logistics | Supplier tech team | $5 k /day LD cap |
| Total landed cost range (5 kL tank) | $50 k – $58 k | $68 k – $80 k | Δ$12 k – $22 k |
Choose FOB when internal freight desk secures < $2.2 /kg air-sea blend and duty drawback available; else DDP to lock maximum exposure.
Phase 5 – Logistics & Insurance
Insure at 110 % of CIF value; require refrigerant leak detector in container—loss events average $14 k per reefer mis-declaration. Mandate desiccant strips and vacuum-packed electronics; humidity >70 % inside crate voids warranty.
Phase 6 – Site Commissioning & Performance Bond
Final 10 % payment released after 30-day reliability run; MTBF ≥ 1 000 h with MTTR ≤ 2 h. Retain 5 % performance bond for 12 months or until 99.2 % uptime demonstrated. Escalation path: 72 h on-site response, 7-day parts dispatch; failure grants buyer right to third-party repair at supplier cost +15 % overhead.
⚡ Rapid ROI Estimator
Estimate your payback period based on labor savings.
Estimated Payback: —
