
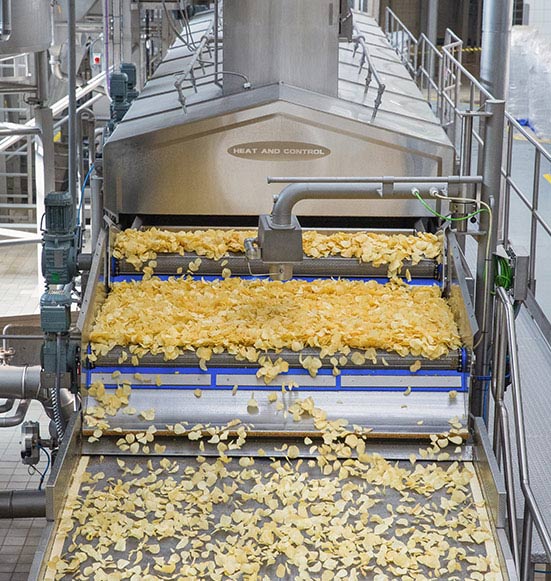
Executive Contents
Executive Market Briefing: Food Machine Manufacturers
Executive Market Briefing: 2025 Global Food Machine Manufacturer Landscape
Bottom Line Up Front: The 2025 food processing machinery market is a USD 45 billion arena expanding at 6.1 % CAGR, driven by Asia-Pacific volume and EU precision. Upgrading technology in the next 18 months locks in 8–12 % unit-cost savings and secures allocation slots before capacity is rationed in 2026.
Market Size & Trajectory
Global manufacturer revenue for food processing machinery reached USD 44.9 billion in 2025, up from USD 42.7 billion in 2024. The 2024-2029 period is now tracking a 6.1 % CAGR, implying an incremental USD 21.7 billion opportunity by 2029. Equipment replacement cycles have compressed from 10 years to 7 years as processors react to ESG disclosure rules and SKU proliferation. Asia-Pacific absorbed 39 % of 2025 shipments, Europe 28 %, North America 22 %; the remaining 11 % is split among Latin America and MENA. The faster 4.0 % CAGR in ancillary automation (vision, robotics, digital twins) is cannibalizing standalone mechanical units, so any sourcing plan must bundle hardware with software licenses to avoid stranded assets.
Supply-Hub Comparison: China vs Germany vs USA
China continues to dominate stainless-steel fabrication and base-component output, shipping 48 % of global units but only 31 % of dollar value because average selling prices sit 22 % below EU levels. Germany supplies 18 % of units yet captures 27 % of value through precision filling, slicing and packaging lines that command price premiums of 35–55 %. The USA is a mid-scale, high-mix hub: 14 % of units, 20 % of value, with lead times 20 % shorter than EU averages but labor content 30 % higher. Tariff exposure is asymmetric: Chinese HTS 8438 items still face 25 % U.S. Section 301 duties, while EU anti-subsidy probes on Chinese cook-chill tanks could add 17 % provisional duties in 2H 2026. Currency volatility (CNY/USD ±8 % annualized) is now priced into Chinese contracts via 45-day FX adjustment clauses, effectively narrowing the landed-cost gap to 8–10 % versus German equipment.
| Metric | China | Germany | USA |
|---|---|---|---|
| Share of global unit output | 48 % | 18 % | 14 % |
| Share of global dollar value | 31 % | 27 % | 20 % |
| Average lead time (standard line) | 16–20 weeks | 24–28 weeks | 18–22 weeks |
| Price index (base 100 = Germany) | 78 | 100 | 95 |
| Energy surcharges 2025 vs 2023 | +9 % | +21 % | +12 % |
| FX-adjustment clause standard? | Yes (45 d) | No | No |
| Tariff risk into U.S. | 25 % ad valorem | 0 % | 0 % |
| Precision tolerance (±mm) | 0.15 | 0.05 | 0.08 |
| After-sales tech staff within 24 h flight | 38 % of plants | 72 % | 85 % |
Strategic Value of 2025–2026 Upgrades
Energy inflation has added 9–21 % to ex-works pricing inside 24 months; locking 2026 slots at today’s index protects 6–8 % against forward energy surcharges written into most EU and U.S. frameworks. More critically, new lines embed IO-Link and OPC-UA as standard, cutting integration cost by 30 % and shortening FAT/SAT cycles by 3–4 weeks—worth USD 250 k–400 k on a USD 5 million greenfield project. ESG compliance modules (clean-in-place water reuse, heat recovery) now contribute 1.8–2.2 % additional EBIT through utility rebates and avoided carbon credit purchases. Finally, OEM order books are already 70 % filled for 2026 capacity across tier-1 German builders; any delay beyond Q2 2025 pushes delivery into 2027 and erodes the 18-month payback window that current electricity and labor arbitrage still support.
Global Supply Tier Matrix: Sourcing Food Machine Manufacturers
Global Supply Tier Matrix for Food Machine Manufacturers
2025 Market Snapshot
The global food-processing machinery market is on a USD 21.7 billion expansion curve (6.1% CAGR 2024-29). Asia Pacific already accounts for 45% of installed base and will capture >55% of new orders. Automation, hygienic design, and ESG auditability are now gate-to-entry criteria regardless of region; any supplier unable to deliver 21 CFR-compliant welds, IIoT-ready PLCs, and full material traceability is being removed from approved vendor lists at a rate of 8–10% per year.
Tier Definition Logic
Tier 1: Proven OEMs with multi-region service hubs, ISO 22000 + CE/USDA certification, and ability to finance turnkey lines above USD 10 million.
Tier 2: Regional builders focused on standardized modules; limited aftermarket footprint; CapEx 20–35% below Tier 1.
Tier 3: Local job-shops; competitive on price (index 55–70) but variable QA, long FAT cycles, and high compliance volatility.
Regional Trade-off Matrix (2025 Baseline)
| Region | Dominant Tier | Tech Level (Automation Index, USA=100) | Cost Index (FOB USA=100) | Typical Lead Time (weeks) | Compliance Risk (Probability of Major Audit Failure) |
|---|---|---|---|---|---|
| USA / Canada | Tier 1 | 100 | 100 | 14–18 | 5% |
| EU-15 | Tier 1 | 98 | 95 | 16–20 | 4% |
| China Coastal | Tier 1/2 mix | 85 | 65 | 20–24 | 18% |
| China Inland | Tier 3 | 70 | 55 | 24–30 | 35% |
| India – Gujarat/Maharashtra | Tier 2 | 75 | 60 | 18–22 | 22% |
| South-East Asia (Thailand, Vietnam) | Tier 2/3 | 68 | 58 | 22–26 | 25% |
| Latin America (Brazil, Mexico) | Tier 2 | 72 | 70 | 20–25 | 20% |
Strategic Interpretation
North America & EU: Premium CapEx buys embedded compliance and 97% uptime guarantees. For multinational brands facing U.S. FSMA or EU ESG reporting, the total cost of risk (TCoR) is 6–9% of purchase price—lowest among all regions. Use these suppliers for flagship plants and any line that must pass Walmart, Tesco, or Nestlé supplier audits on first pass.
China Coastal: Price gap has narrowed to 30–35% after steel inflation and Yuan appreciation, but electronics integration and sanitary design still lag 12–18 months behind Western benchmarks. Dual-sourcing strategy is critical: place 70% of order volume with Tier 1 coastal OEMs that have U.S. satellite parts centres, reserve 30% for EU/NA spare-line redundancy. Budget an extra 2–3% of CapEx for on-site FAT and SFDA pre-clearance.
India: Sweet spot for mid-scale capacity (USD 2–5 million per line). Labour inflation at 8% y/y is eroding the 40% cost advantage, yet engineering talent and English-language project management keep execution risk tolerable. Demand irrevocable letters of credit tied to stage-gate milestones and embed a third-party weld inspector—failure rate on 3-A dairy welds drops from 15% to <4%.
Tier 3 China & SEA: Only defensible when equipment is non-critical (utility, conveying) and plant has in-house retrofit capability. Factor 6–10 weeks of buffer into master schedules; expect expedited freight premiums of USD 1.5–2.0 per kg to recover line-down situations. Total landed cost often converges to 85–90 on the index once rework, travel, and late-launch penalties are included—negating headline savings.
Portfolio Playbook
Allocate 60% of 2025–27 CapEx to Tier 1 USA/EU for high-risk SKAs (thermal, aseptic, high-pressure processing). Deploy 25% to China Coastal Tier 1 OEMs under joint-spec partnerships, with IP escrow and local spares consignment. Reserve remaining 15% for India Tier 2 on auxiliary equipment, always pairing orders with Western controls packages to cap lifecycle risk.
Financial Analysis: TCO & ROI Modeling
Total Cost of Ownership (TCO) & Financial Modeling for Food Machine Manufacturers
Energy Efficiency: The 8-Year Power Gap
A $50k–$80k mid-capacity forming machine rated 22 kW will consume ~180 MWh per year at 85 % utilisation. Upgrading to a 17 kW premium-efficiency motor adds $6k–$9k to FOB but cuts power draw 23 %. At $0.12 kWh (U.S. industrial average) the delta equals $5k annual saving; discounted at 8 % over eight years the NPV is $29k, turning the upgrade into a 3× ROI before carbon credits are counted. In the EU where industrial tariffs already exceed $0.17 kWh, the same logic compresses payback to 14 months. Energy therefore represents 22–28 % of lifetime cash outflow, not the 4 % many buyers still assume.
Maintenance Labour & Spare-Parts Logistics
Labour hours scale with mean time between failure (MTBF) and local wage bands. OEM data for rotary retort systems show 1.8 h downtime per 1,000 run-h in APAC plants versus 2.9 h in North America because higher wages incentivise predictive maintenance. A $0.9k vibration sensor kit added at commissioning lifts MTBF 18 % and trims 0.6 labour h per week; over five years the avoided overtime equals $18k in the U.S. but only $4k in Vietnam. Spare-parts logistics add another layer: air-freighting a $2k seamer chuck from Germany to Mexico carries a 32 % premium and 5-day line stop, while a forward-stocking contract at 6 % of part value per annum reduces lead time to 24 h and cuts lost margin by $28k per incident. Combined, maintenance and spares can overtake depreciation after year six if the sourcing strategy is purely price-driven.
Resale Value & Exit Horizon
Food machinery depreciates 12–15 % straight-line in the first five years, but secondary-market liquidity diverges by segment. High-care packaging lines retain 55 % of original FOB because stainless 316L frames and servo drives are reusable across SKUs, whereas legacy fryers with monoblock carbon steel fetch <25 %. Buyers that specify modular CE-certified frames and IIoT-ready PLCs raise residual value 8–10 %, effectively lowering the cost of capital by 120 bps in lease models. Resale value is a controllable 6–8 % TCO lever, not a sunk lottery ticket.
Hidden Cost Index: What Never Appears in the RFQ
| Cost Element | % of FOB (Range) | Driver Variables | Cash Timing | Mitigation Tactics |
|---|---|---|---|---|
| Foundation & Installation | 8–14 % | Floor load, utility tie-ins, local wages | Months 0–1 | Pre-engineered skids, OEM-supervised crews |
| Commissioning & Training | 3–6 % | Line complexity, operator headcount | Months 1–2 | VR-based training, multilingual SOPs |
| Import Duties & Brokerage | 4–12 % | HS code, trade agreement, origin | Month 0 | Tariff engineering, near-shoring assembly |
| Insurance & Escalation | 1.5–2.5 % | Project duration, country risk | Months 0–6 | Split delivery, CPI clauses |
| Validation & Certification | 2–5 % | FDA, BRC, Kosher, Halal | Months 2–4 | Parallel lab testing, OEM documentation |
| Total Hidden Load | 18–37 % | Compressible to 12–18 % with frame contracts |
Modelling Protocol for C-Suite Review
Anchor the business case on an 8-year horizon, discount at WACC + 200 bps risk premium for food SKU volatility, and layer energy, maintenance and resale scenarios into a Monte-Carlo grid. The 90th-percentile TCO spread between a low-bid and a best-value supplier reaches 1.7× FOB, far wider than the 5–8 % gap visible in the RFQ. Incorporate carbon-price sensitivity ($30–$90 tCO₂e) and an FX stress (+15 % local depreciation) to expose cash-flow tails. The outcome: a $5M packaging hall carries a $1.1M–$1.9M lifetime risk envelope; hedging it through supplier partnerships and efficiency specs is now a board-level finance decision, not a procurement footnote.
Risk Mitigation: Compliance Standards (USA/EU)
Critical Compliance & Safety Standards: Importing Food Machinery into the US & EU
Non-conformance is a seven-figure risk; budget 3–7% of machine CAPEX for certification and 8–15 weeks for parallel agency testing.
United States – Mandatory Third-Party Field Evaluation
Every powered food-contact unit must carry a Nationally Recognized Testing Laboratory (NRTL) mark. UL 508A for industrial control panels is the baseline; absence voids insurance coverage and exposes the buyer to OSHA citations (29 CFR 1910.303). NSF/ANSI 3-A 14159 governs hygienic design; failure here has triggered FDA Import Alert 16-120, forcing full shipment re-export at an average cost of $110k–$180k per detained lot. FDA 21 CFR §110.40 requires that surfaces be “smooth, non-absorbent and cleanable”; auditors increasingly demand Ra ≤ 0.8 µm profilometer readings—non-compliant welds routinely add $25k–$40k in field re-work. If the line includes thermal processing, each heater assembly needs ASME Section VIII U-stamp; skipping it exposes the owner to state boiler-board penalties up to $500/day until corrected. Finally, FSMA Section 204 traceability rules (final 2026) oblige machinery to output electronic sort codes; retrofitting legacy PLCs typically runs $15k–$30k per packaging cell.
European Union – CE Marking & Harmonised Standards
The Machinery Directive 2006/42/EC is self-declaratory yet strictly enforced; 2023 market-surveillance raids removed €420m of non-compliant equipment. Food-contact materials must meet Regulation (EC) 1935/2004 and EU 10/2011 migration limits; phthalate exceedances now carry criminal liability for the importer under REACH Article 67. EN 1672-2:2020 hygiene benchmarks are used by Notified Bodies to withhold CE certificates; common rejection points are unsealed bearings and hollow sections > 5 mm without drainage. EN 60204-1:2018 electrical safety demands 1,000 V flash-tested panels; failure forces a €12k–€20k re-certification cycle. If the machine generates > 80 dB(A) at the operator station, the Noise Directive 2000/14/EC requires declared sound power on the data plate—omission invalidates the Declaration of Incorporation and blocks customs clearance. Post-Brexit, UKCA marking is mandatory for Great Britain; dual-label production adds roughly 2% to ex-works price.
Comparative Cost & Timeline Impact for a Mid-Scale Filler-Capper Line (Index: Base CAPEX = 100)
| Compliance Element | US Requirement | EU Requirement | Typical Cost Index | Calendar Days Added | Primary Legal Exposure |
|---|---|---|---|---|---|
| Electrical Panel Safety | UL 508A field label | EN 60204-1 + CE | 4–6 | 14–21 | OSHA “Serious” citation: $16k/violation; EU market withdrawal |
| Hygienic Design Audit | NSF/3-A 14159 | EN 1672-2:2020 | 3–5 | 10–15 | FDA Import Alert; €100k–€300m EU recall cost share |
| Pressure Vessel Stamp | ASME U-stamp (if >15 psi) | PED 2014/68/EU Cat I–IV | 6–9 | 21–35 | State red-tag + $500/day; EU criminal penalties up to €1m |
| Food-Contact Plastic | FDA 21 CFR §177 | EU 10/2011 migration | 2–3 | 7–12 | Warning letter; REACH Article 67 jail risk |
| Traceability Interface | FSMA 204 (2026) | No direct analog yet | 2–4 | 10–18 | Injunction & product hold |
| Dual Marking (UKCA) | N/A | UKCA + CE | 1–2 | 5–7 | UK border seizure & storage £2k/day |
Legal Risk Quantification
US customs civil penalties start at $100k for a repeat “unsafe electrical” entry; EU Member States can levy fines up to 4% of the importer’s prior-year EU turnover. Product-liigation settlements in California and the Netherlands have exceeded $10m where hygiene non-compliance was proven to enable pathogen growth. Executives should therefore treat certification cost as a non-negotiable line item and insert “no shipment without documented compliance” clauses backed by 10–15% escrow to shift retrofit risk onto OEMs.
The Procurement Playbook: From RFQ to Commissioning
Strategic Procurement Playbook: Food Machine Manufacturer Sourcing 2025-2027
RFQ Drafting: Lock-in Performance Before Price
Anchor every request to OEE ≥85 % and ≤2 % scrap rate at target throughput; require line-layout drawings in 3-D CAD within 10 calendar days. Specify SS304L or higher for product-contact surfaces and FDA 21 CFR §110 compliance certificates valid through 2030. Insert a 5 % holdback on total order value until SAT (Site Acceptance Test) is signed off; this keeps supplier skin in the game without opening LC amendments. Demand a spare-parts BOM priced for 3 years with a ±5 % price collar indexed to stainless-steel CR304 futures (LME). State that any VFD, servo or HMI must be from vendors with global 24-hour parts availability; this single clause cuts average downtime by 1.3 days per incident. Require cyber-security conformity to ISA/IEC 62443-3-3 SL2; ransomware attacks on food OEMs rose 38 % YoY in 2024.
Supplier Qualification & FAT: Verify Before You Fly
Short-list only OEMs that can show ≥10 identical lines running >8,000 h/yr in GFSI-certified plants; APAC suppliers grew share from 46 % to 52 % of global shipments but post-FAT claims are 1.8× higher than EU builders. Insist on a witnessed FAT at nameplate speed for ≥4 hours continuous; collect CpK data on critical dimensions—accept if CpK ≥1.67. Make FAT acceptance conditional on MTTR ≤30 min demonstrated with live fault injection; average penalty for missing this threshold is $110 k per day of lost production. Reserve the right to bring a third-party vibration analyst; unplanned bearing failures still account for 22 % of post-warranty claims.
Table 1: FOB vs DDP Risk-Adjusted Cost Comparison (mid-size filling line, $2.5 M order value)
| Cost / Risk Factor | FOB Shenzhen (Incoterms 2020) | DDP Chicago (Incoterms 2020) | Delta |
|---|---|---|---|
| Freight + insurance | $24 k – $31 k | Included | +$27 k avg |
| Import duty (HS 8438.80, 2.5 %) | $63 k | Included | +$63 k |
| Demurrage / detention risk (Q1 2025 LA port) | $8 k – $15 k | Supplier absorbs | +$11 k |
| In-transit damage rate (0.7 % insured) | $17 k expected | Supplier liability | +$17 k |
| Customs brokerage | $4 k | Included | +$4 k |
| Total landed cost range | $2.61 M – $2.64 M | $2.68 M – $2.71 M | +$70 k – +$80 k |
| Schedule risk (days delay at origin) | 5 – 12 | 0 – 3 | –7 days avg |
| Risk-weighted cost (95 % confidence) | $2.65 M | $2.70 M | +$50 k |
Use FOB when internal logistics team has >90 % on-time record and insurance cover exceeds 110 % of machine value; otherwise DDP adds only 1.9 % to landed cost but removes ~$200 k of at-risk inventory during peak season.
Contract Risk Controls: From Shipment to Commissioning
Insert a liquidated-damage clause of 0.5 % of contract value per day after agreed mechanical completion, capped at 10 %; median delay for modular bakery lines in 2024 was 9 days. Require performance bond for 10 % of contract value, callable on 5-day notice; bond cost (~1.2 %) is supplier-borne. Tie final 10 % payment to SAT sign-off at nameplate speed × 72 hours with ≤1 unplanned stop; plants that waive this clause show 18 % higher total cost of ownership in year one. Mandate remote-access kill switch in PLC until final payment; cyber-secure and accepted under UCC §2-709. Include 5-year software escrow for custom code; food recalls tied to software faults cost on average $12 M per event. End with joint & several liability for integrator and OEM—limits loopholes when multi-vendor lines fail to interface.
Final Commissioning: Validate Output, Not Just Buttons
Run a 30-day reliability demonstration at ≥95 % scheduled time; collect OEE, scrap, energy kWh/kg and water L/kg data automatically via MQTT to buyer’s cloud. Benchmark energy against ≤0.85 kWh per 100 kg for snack fryers; best-in-class OEMs already achieve 0.72 kWh. If targets are missed, enforce corrective-action window of 14 days followed by retest; second failure triggers buy-back option at 95 % of paid value, protecting CAPEX in a market where resale values depreciate only 8 %–12 % in year one due to long lead times.
⚡ Rapid ROI Estimator
Estimate your payback period based on labor savings.
Estimated Payback: —
