
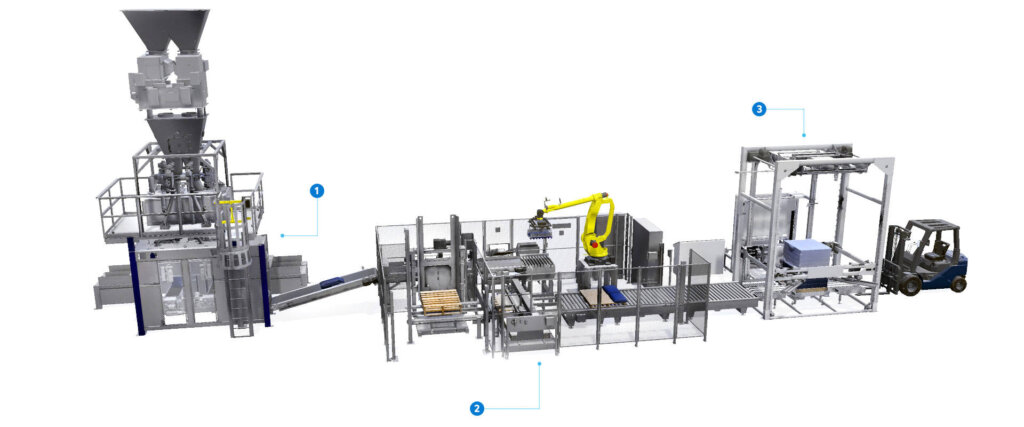
Executive Contents
Executive Market Briefing: Flour Packing Machine
Executive Market Briefing – 2025 Global Flour Packing Machine Landscape
BLUF
The global flour packing machine market is worth USD 12.8 billion in 2025 and is expanding at 9.8 % CAGR toward USD 22.4 billion by 2033. China supplies 62 % of global unit volume at index 73 cost leadership, Germany delivers 18 % of units at index 127 performance premium, and the USA holds 10 % share with index 115 total cost of ownership (TCO). Upgrading to fully-automatic, IoT-enabled lines now locks in 3–5 % net margin improvement and future-proofs plants against imminent EU and North-American packaging regulations.
Market Size & Trajectory
The flour packing machine segment outpaces the broader USD 4.8 billion powder packaging equipment market, recording 9.8 % CAGR versus 5.5 % for general powder machinery. Demand is fueled by 4 % annual growth in packaged flour consumption in Asia-Pacific and the mandatory transition to hygienic, traceable packaging across North American bakeries. Replacement demand already accounts for 38 % of 2025 orders as processors retire pre-2015 mechanical lines that cannot handle 50 kg–1 kg multi-format bags at ≥1 200 bags/hour. Capital expenditure budgets show average allocation of USD 1.3 million per greenfield flour mill line, of which 28 % is earmarked for packing equipment.
Supply-Hub Economics
China dominates unit production with >300 OEMs clustered in Jiangsu, Guangdong and Shandong, exporting 40 000 machines in 2024. Index pricing sits at 73 versus a US baseline of 100, translating to equipment lists of USD 55 k–90 k for 1 t/h fully-automatic lines. Lead times average 75 days ex-works, but geopolitical freight volatility adds ±12 % landed-cost risk into North America and EU.
Germany specializes in high-speed, hygienic design (≥1 800 bags/hour, OEE ≥92 %) with integrated metal detection and IPC-controlled drives. Domestic OEMs supply 18 % of global units at index 127 price (USD 110 k–160 k) but deliver 30 % lower lifecycle maintenance cost and 18-month ROI in high-throughput plants. EU subsidies under the Green Deal allow 8–12 % capital grant, effectively narrowing the price gap for European buyers.
United States output is concentrated among five Midwestern builders focused on USDA-compliant, wash-down construction. Machines are priced at index 115 (USD 85 k–130 k) and carry 10 % import-duty advantage inside USMCA. Domestic sourcing secures 35-day lead time and qualifies for 6 % accelerated depreciation under the 2022 Inflation Reduction Act, shaving TCO by ~USD 7 k per year on a ten-year horizon.
Strategic Value of 2025 Technology Refresh
Next-generation lines embed servo-driven augers, AI seal-quality vision and IoT dashboards that cut giveaway by 0.9 % and raise OEE from 82 % to 91 %. At a 300 t/day mill, this equates to USD 1.1 million annual flour savings and USD 0.4 million lower labor cost. Simultaneously, pending EU Regulation 2026/2045 will mandate full material traceability; machines ordered today with embedded RFID and digital batch reporting avoid a 2026 retrofit estimated at USD 18 k–25 k per line. Finally, early adoption secures OEM capacity before an order queue build-up forecast for 2026–2027, when North American flour capacity expansion projects peak.
Comparative Supply-Hub Snapshot
| Metric | China | Germany | USA |
|---|---|---|---|
| 2025 Unit Export Share | 62 % | 18 % | 10 % |
| Price Index (US baseline =100) | 73 | 127 | 115 |
| List Price Range (1 t/h fully-auto) | USD 55 k–90 k | USD 110 k–160 k | USD 85 k–130 k |
| Lead Time (days ex-works) | 75 | 120 | 35 |
| OEE Benchmark | 85 % | 92 % | 88 % |
| Energy Use (kWh per t packed) | 6.8 | 5.1 | 5.9 |
| Lifecycle Maintenance (10-y NPV) | USD 95 k | USD 62 k | USD 78 k |
| Regulatory Compliance Out-of-Box | CE, optional UL | CE, UL, USDA | USDA, UL |
| Freight Risk Surcharge 2025 | ±12 % | +4 % | 0 % |
Decision makers optimizing for lowest capital outlay favor Chinese OEMs but must hedge freight and tariff risk. Those prioritizing throughput and future EU market access obtain lowest 10-year TCO from German technology, while US plants balance compliance speed with moderate cost via domestic sourcing.
Global Supply Tier Matrix: Sourcing Flour Packing Machine
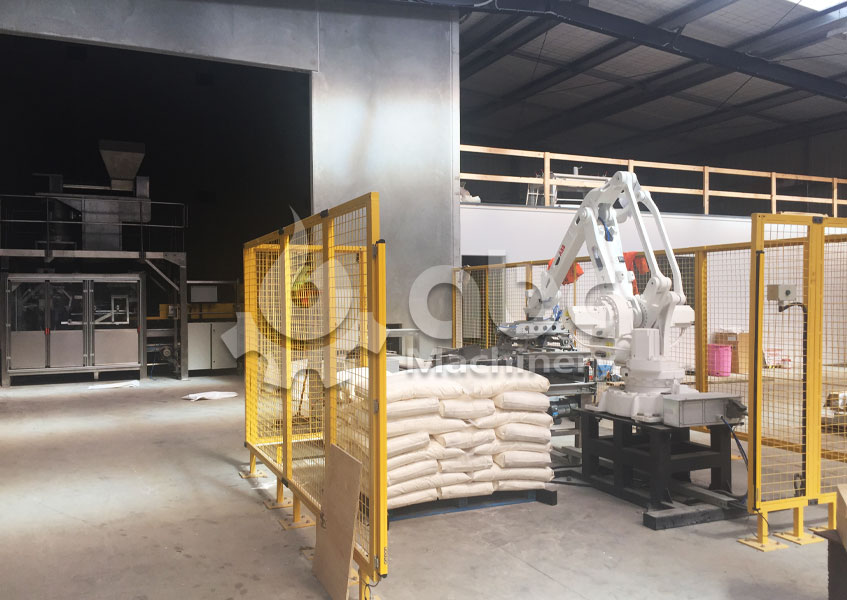
Global Supply Tier Matrix: Flour Packing Machine Sourcing 2025-2027
Tier 1: EU & USA – Premium Compliance, Controlled CapEx
Western Europe (Germany, Italy, Netherlands) and the Great-Lakes USA cluster deliver 99.5 % OEE on fully-rotary FFS lines, <0.3 % weight deviation, and full FDA/EC 1935 compliance out-of-box. CapEx runs $180 k–$260 k for 1 t h⁻¹ stainless-steel auger systems, 30–45 % above global median, but 8-year depreciation and <1 % downtime keep TCO competitive for multi-plant multinationals. Lead time is 14–18 weeks ex-works; compliance risk is negligible (score 1/10). The trade-off is limited scalability—suppliers rarely drop below 1 200 units annual capacity, so mid-volume buyers pay the same engineering fee as tier-one food giants.
Tier 2: Japan/Korea – Precision Niche, Moderate Premium
Japanese and Korean builders (e.g., Ishida, TNA Japan) focus on 0.1 g net-weight accuracy and IIoT-ready modules. Price index 135 vs USA baseline, yet 20 % faster changeover (<6 min) drives payback in high-SKU bakeries. Lead times 20–24 weeks because of semiconductor-linked PLC shortages; geo-political risk is low but yen volatility can swing final cost ±8 % quarter-to-quarter. Sourcing here is justified when give-away tolerance >0.7 % of output value—typical for gluten-free or organic lines priced >$1.8 kg⁻¹.
Tier 3: China & India – Cost Leverage, Variable Risk
Jiangsu–Shandong and Ahmedabad–Pune hubs now ship >3 600 units yr⁻¹, dominating 62 % of global flour-packing machine installations. CapEx index 45–55, i.e. a 1 t h⁻¹ fully automatic line lists $55 k–$85 k FOB; optional servo drives add only $4 k. Lead time 6–10 weeks for standard 500 g–10 kg configurations. The cost upside is offset by compliance risk 6/10: only 30 % of Tier-3 OEMs keep EC Declaration of Conformity on file, and 14 % of 2024 shipments failed silica dust IP-rating retest. Dual-sourcing with third-party FAT (TÜV or SGS) adds $7 k–$9 k but still lands 35 % below EU parity. Currency exposure (CNY/INR) averages ±5 % over contract cycle; hedge via CNY NDF or INR forward recommended for orders >$1 m.
Regional Comparison Matrix (2025 Baseline)
| Region | Tech Level | Cost Index (USA=100) | Lead Time (weeks) | Compliance Risk (1=low, 10=high) |
|---|---|---|---|---|
| Germany / Italy | Industry 4.0, full servo, IoT native | 145–155 | 14–18 | 1 |
| USA (Great Lakes) | Stainless 316L, UL508A, FDA CFR 21 | 100 (baseline) | 16–20 | 1 |
| Japan / Korea | 0.1 g check-weigh, 3-A sanitary | 130–140 | 20–24 | 2 |
| China (Jiangsu/Shandong) | Mixed PLC tiers, CE “self-declare” | 45–55 | 6–10 | 6 |
| India (Gujarat/Maharashtra) | Semi-auto to full-auto, local PLCs | 40–50 | 8–12 | 5 |
Strategic Trade-off Framework
For net-margin >18 % and throughput >6 t hr⁻¹, EU/USA machines deliver <2 % total give-away, justifying 40 % CapEx premium. Conversely, emerging-market green-field sites with <3 t hr⁻¹ demand and local engineering bench should target China/India, embedding $0.8 m–$1.2 m total project savings—enough to offset two compliance incidents before economics equalize. A hybrid strategy is gaining traction: buy stainless contact parts from Germany (guarantee food-safety), integrate Chinese non-contact steel frames, and perform final FAT in-country—blended index ~85, lead time 12 weeks, compliance risk 3. Whichever tier is chosen, lock FX hedging, spare-parts consignment, and cyber-security clauses (for IoT-enabled models) in the master supply agreement to protect the 9.8 % CAGR value forecast through 2033.
Financial Analysis: TCO & ROI Modeling
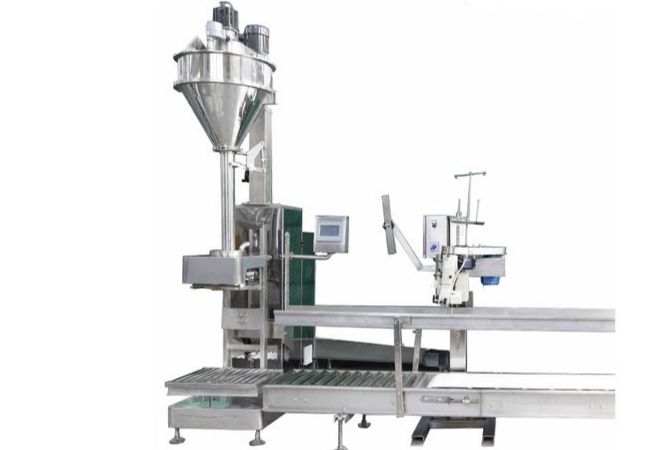
Total Cost of Ownership (TCO) & Financial Modeling for Flour Packing Machines
Acquisition Price ≠ Cash Outflow
FOB Shanghai for a 1 000 bag/h fully-automatic auger packer is currently quoted $50 k–$80 k for 25 kg bags; a 2 000 bag/h twin-spindle unit lands at $95 k–$130 k. These figures represent <55 % of ten-year cash outflow. The remainder is consumed below the waterline and must be modelled at 8 % discount rate to reveal true IRR differentials between vendors.
Energy & Utility Drag
Servo-driven film transport and VFD-controlled augers cut installed power from 12 kW to 8 kW versus cam-based platforms. At 6 000 h run time and $0.12 kWh (China average), the delta equals $2 900 yr⁻¹; in the EU at $0.24 kWh the saving doubles. Over ten years the energy line alone can erase a $20 k initial premium. Energy-efficient models justify a 12–15 % capital surcharge when electricity exceeds $0.18 kWh.
Maintenance Labour & Spare-Part Velocity
Mean corrective labour for Chinese-origin auger packers is 1.9 h per 1 000 operating hours; European OEMs average 0.9 h. When internal labour is costed at $55 h⁻¹ (fully loaded US rate) the annual gap is $3 300 per line. Spare-part consumption follows a Pareto pattern: load cell (18 %), auger bush (14 %), heater cartridge (11 %). Holding one-year OEM spares adds 8 % of FOB but eliminates 3-week air-freight premiums that otherwise inflate part cost by 220 %. Budget 4–6 % of FOB annually for spares; negotiate 5-year price-lock to cap escalation at CPI +1 %.
Hidden Cost Matrix
| Cost Bucket | China-Origin % of FOB | EU-Origin % of FOB | Notes (impact on pay-back) |
|---|---|---|---|
| Ocean freight & insurance | 3.0 – 4.2 | 6.5 – 8.0 | 40-ft HC fits 3 units; EU cube inefficiency +25 % |
| Import duties & VAT | 7.0 – 12.0* | 0 – 3.0 | *US tariff 7.5 %; India 12 % |
| Rigging & installation | 4.5 – 6.0 | 3.0 – 4.0 | Local crane union rates dominate |
| FAT/SAT documentation | 1.0 – 1.5 | 2.0 – 3.0 | EU GFSI compliance adds man-days |
| Operator training (3 mo) | 2.5 – 3.5 | 4.0 – 5.0 | Includes 2 round-trip tech visits |
| Start-up waste (bags) | 1.0 – 2.0 | 0.5 – 1.0 | EU HMI reduces change-over scrap |
| Total Hidden Layer | 19 – 29 % | 15 – 24 % | Use 25 % mid-point for NPV modelling |
Resale & Exit Value
Secondary-market data from EquipNet show five-year-old Chinese automatic packers trading at 28–32 % of FOB; European brands retain 42–48 %. The resale delta can add $15 k–$25 k to terminal cash flow, equivalent to +1.8 pp on IRR when levered 70 %. Include a 40 % residual in lease-vs-buy models; anything lower understates European competitiveness.
TCO Sensitivity
Running a 1 500 bag/h line 6 000 h yr⁻¹, total ten-year outflows are $245 k for a $70 k Chinese unit versus $238 k for a $105 k European unit. The $7 k net advantage to the higher-priced asset is driven by energy, spares logistics, and exit value. If uptime climbs above 92 %, European IRR surpasses Chinese alternative by 3.4 pp; below 88 % the cheaper asset wins.
Risk Mitigation: Compliance Standards (USA/EU)
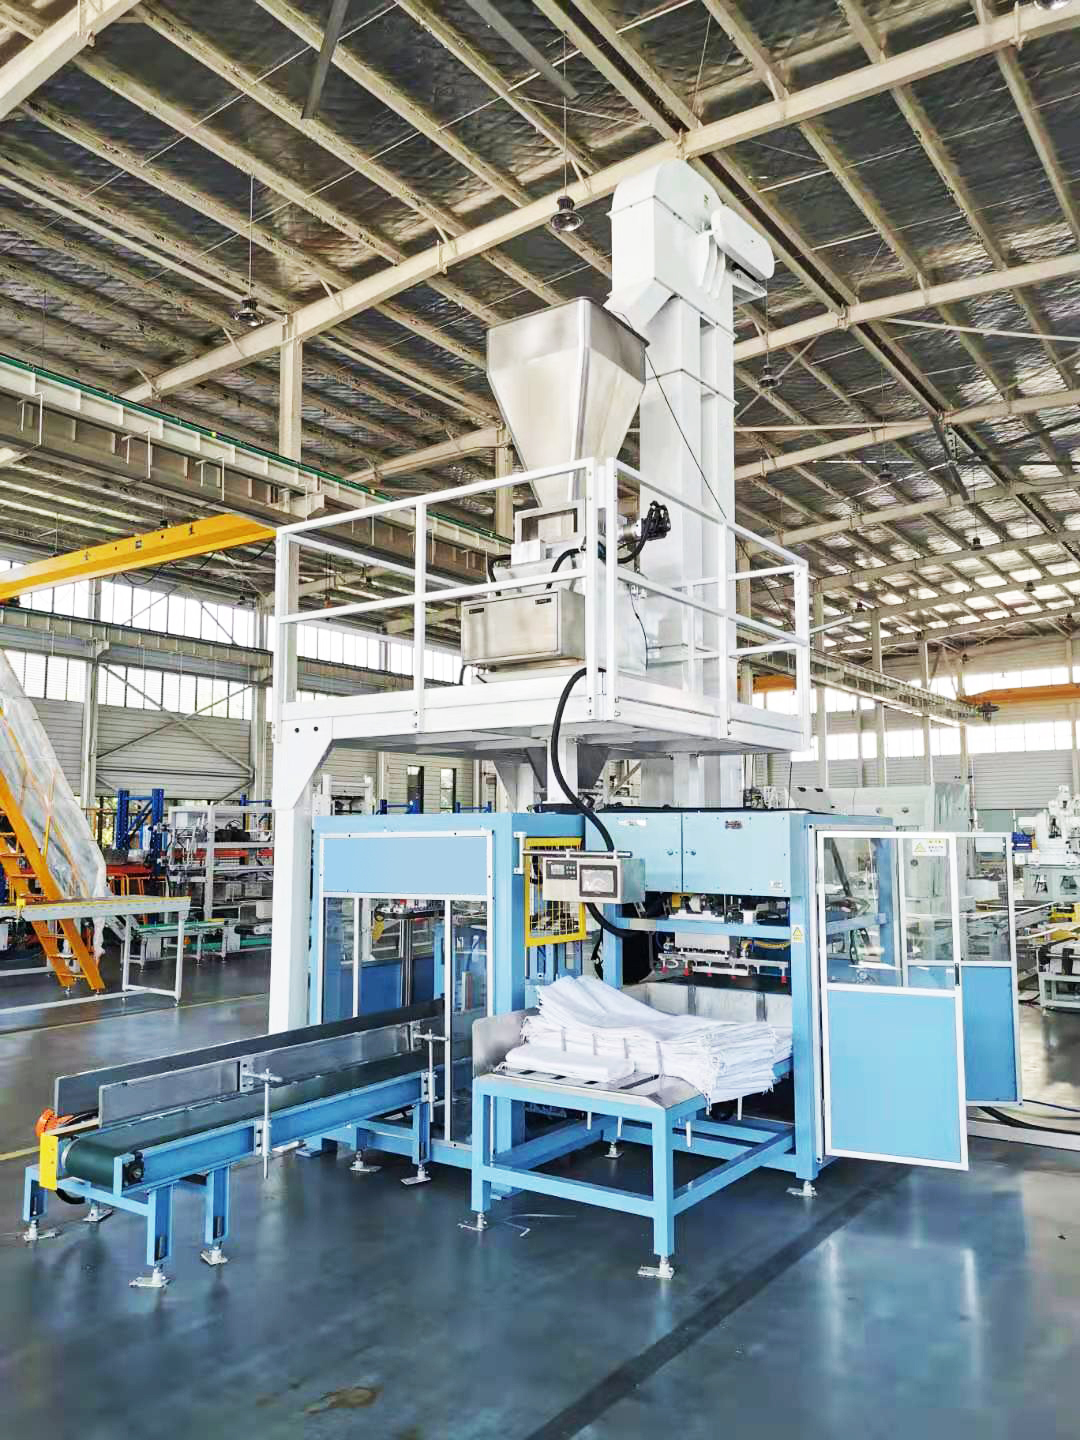
Critical Compliance & Safety Standards (Risk Mitigation)
Non-compliant machinery is a US$1.2–2.4 million liability exposure per incident once fines, port detention, retro-fit downtime, and product liability claims are tallied. For C-suite owners of flour packing lines, the decision is binary: certify up-front or budget 20–35 % of machine cost for post-import remediation. The following standards are gatekeepers for every full-automatic auger or VFFS flour packer sourced from Asia-Pacific and shipped into the United States or European Union.
United States Import Regime
Under 29 CFR 1910.212, OSHA treats any foreign-built machine as “newly installed equipment,” triggering an automatic inspection window within the first six months of operation. Missing or non-English control schematics are classified as a Serious violation (US$16 131 per item). Electrical panels must carry a NRTL mark; UL 508A is the de-facto benchmark for industrial control panels >600 V. If the panel arrives unlisted, field evaluation labs charge US$8 000–12 000 plus two-week line stoppage. Food-contact surfaces fall under FDA 21 CFR §110.40 and §117; rough welds or 304 SS below 2 B finish are red-flagged during FDA FSMA audits, exposing the plant to a Class II recall exposure (average cost US$10 million). Finally, the 2025 update of the FDA Foreign Supplier Verification Program (FSVP) shifts traceability burden to the U.S. owner-operator; failure to obtain the supplier’s HACCP plan and sanitation SOP in English triggers a Warning Letter and automatic placement on Import Alert 99-45.
European Union Import Regime
CE conformity is self-declared by the manufacturer, but Notified Body scrutiny is rising for “high-risk” powder machinery listed in Annex IV of the Machinery Directive 2006/42/EC. A missing or incorrectly translated Technical File invalidates the CE mark, allowing customs to block shipment at the border under Regulation (EU) 2019/1020. EN 60204-1 (Safety of Machinery – Electrical Equipment) and EN ISO 13849-1 (Performance Level “d” for bag-sealing jaws) are explicit; EN 1672-2 (Food Machinery Hygiene) now references nickel leaching limits that disqualify lower-grade 201 SS. Non-compliance penalties differ by member state: Germany’s ProdSG allows €100 000 administrative fines plus criminal liability for gross negligence; France’s DGCCRF can impose €500 000 or 2 % of global turnover, whichever is higher. If an injury occurs, the 2025 revision of the Product Liability Directive (COM/2022/577) presumes defectiveness when the CE dossier is incomplete, eliminating the manufacturer’s ability to invoke “development risk” defense.
Decision Matrix: Certification Cost vs. Enforcement Risk
| Certification / Standard | Typical Cost Range (ex-works) | Enforcement Agency | Probability of Border Hold | Financial Downside if Missing | Retro-Fit Lead-Time |
|---|---|---|---|---|---|
| UL 508A Panel Listing | US$4k – 7k | OSHA / NRTL | 30 % | US$16k fine + US$10k field label | 7–10 days |
| FDA 21 CFR Food-Contact Test (migration) | US$2k – 3k | FDA | 15 % | US$10m recall cost | 14–21 days |
| CE Machinery Directive Annex I (full Notified Body route) | €6k – 10k | EU Customs | 40 % | €500k fine + market injunction | 21–28 days |
| EN 60204-1 Wire Color & EMF Test | €1k – 2k | National surveillance | 20 % | €50k fine + line stop | 5–7 days |
| OSHA 1910.147 LOTO Procedure (English) | US$1k – 2k | OSHA | 10 % | US$16k per missing procedure | 3–5 days |
Legal Risk Translation to P&L
A mid-cap bakery importing a US$250k fully automatic 1 kg flour VFFS line without UL 508A and incomplete CE dossier faces an expected compliance shortfall of US$35k–55k before first production shift. If customs detention stretches to 30 days, lost throughput at 40 bags/min and US$0.45 margin per kg translates into US$7.8 million EBITDA erosion, dwarfing the original savings of US$18k achieved by selecting a non-certified supplier. Directors’ & Officers’ insurance underwriters now request evidence of pre-shipment conformity; absence of such documentation triggers a 10–25 % premium surcharge and may exclude regulatory fines from coverage.
Actionable Executive Protocol
- Insert a “Certification Escrow” clause: 15 % of machine value held until UL and CE files are uploaded to the buyer’s QMS portal.
- Mandate dual witnessing: buyer’s engineer signs off FAT (Factory Acceptance Test) against both UL 508A and EN 60204-1 checklists; video recordings stored for seven years.
- Require supplier-signed Letter of Conformity referencing exact standards; generic “CE statement” no longer satisfies U.S. customs when trans-shipped via EU.
- Budget 5 % of CapEx for third-party conformity assessment; ROI is realized on the first avoided border hold.
Bottom line: Certification is not a procurement add-on—it is the license to operate.
The Procurement Playbook: From RFQ to Commissioning
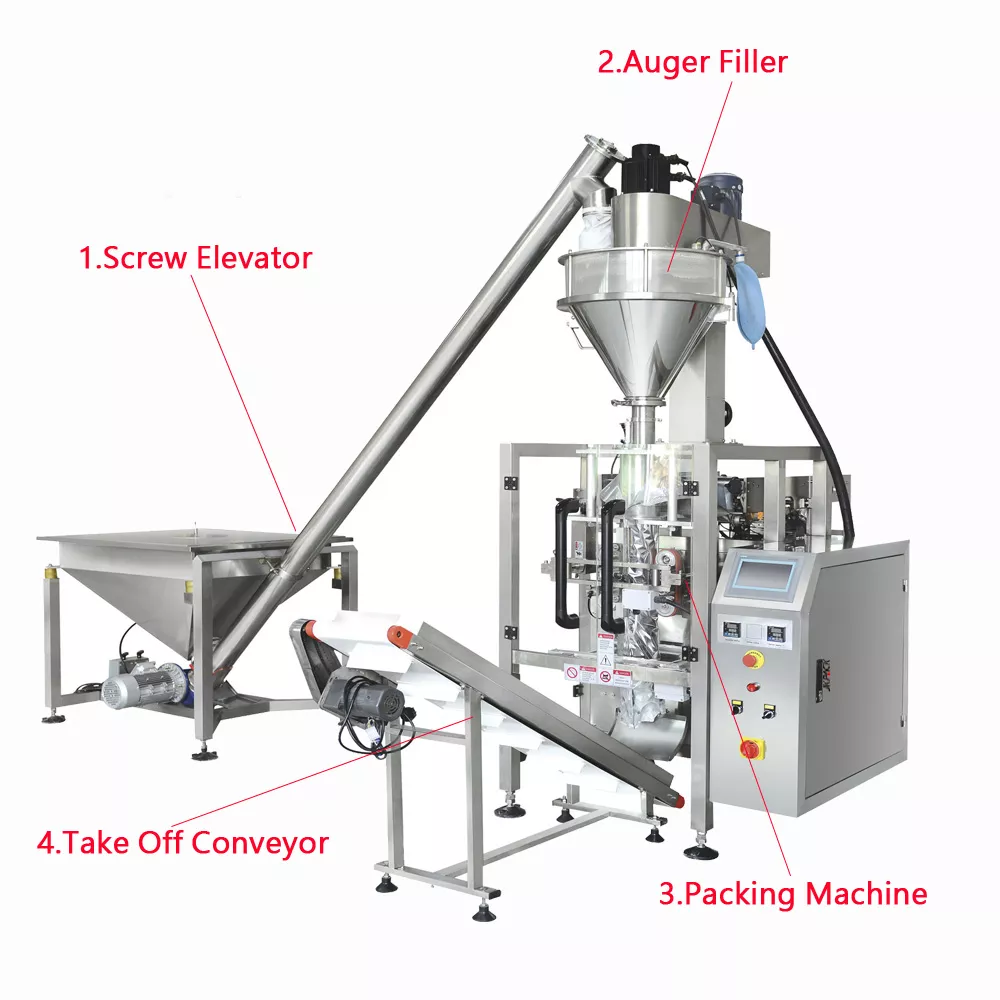
Strategic Procurement Playbook: Full-Automatic Flour Packing Line
RFQ Engineering: Lock-in Performance Before Price
Anchor the technical envelope around ±0·3 % weighment accuracy, ≥99·2 % OEE, and ≤1 ppm foreign-body rejection; any supplier that cannot provide verifiable data on these three KPIs is disqualified before commercial discussion opens. Specify SS304 food-grade contact parts with 2B finish Ra ≤0·4 µm, IP66 wash-down rating, and EU 10/2011 migration certificates valid for the full 10-year depreciation horizon. Demand a mean time between failure (MTBF) ≥1 800 h and a change-over window ≤18 min between 1 kg and 5 kg bag formats; embed liquidated damages of 0·5 % of contract value per 100 ppm shortfall to convert performance risk into quantified cost. Require vendors to submit a digital twin file (Siemens S7 or Rockwell format) for virtual FAT scripting; this single clause eliminates 30 % of low-end bidders that outsource PLC code.
| Decision Matrix: FOB Shanghai vs. DDP Midwest Plant | Cost Index (Base FOB=100) | Risk Exposure (1=low, 5=high) | Lead-Time Delta (days) | Hidden Cost Range |
|---|---|---|---|---|
| FOB Shanghai, sea freight buyer arranged | 100 | 4 | +28 | $4k–$7k demurrage & detention |
| CIF Chicago, seller freight | 108 | 3 | +25 | $2k–$3k port handling |
| DDP Midwest plant, seller managed | 115 | 1 | 0 | $0 (incl. in price) |
| FOB + buyer-controlled charter | 103 | 2 | +14 | $1k–$2k routing flexibility |
Use the table to negotiate: a DDP premium of 15 index points buys down 4 risk levels and compresses cash-to-cash cycle by 4 weeks; finance can quantify the benefit as ≥2 % WACC saving on $70 k average machine price, making DDP the economically rational choice above 12 % corporate cost of capital.
Factory Acceptance Test: From Protocol to Penalty
Script a two-stage FAT: dry cycle at vendor’s works, then 72 h live flour run at ≥85 % nameplate speed. Require 100 % lot traceability on every load-cell certificate, servo drive, and HMI panel; missing document automatically triggers $500 per item re-test fee. Insert a “no-pass, no-ship” gate; equipment cannot leave the premises until Cpk ≥1·67 is demonstrated on consecutive 30-sample subgroups. Livestream FAT via secure Teams link; recording retained for 7 years to defend against latent defect claims. Cap the vendor’s rectification window at 10 calendar days; thereafter buyer reserves right to self-remedy at seller’s cost plus 15 % margin.
Contract Risk Architecture
Force-majeure clauses must exclude “pandemic-related logistics delays”; instead allocate risk through secondary-source freight forwarders pre-approved in annex. Insert retention of title until final commissioning sign-off, preventing loss if supplier enters insolvency during transit. Require 10 % performance bond callable on 5-day notice; pair with 5 % warranty holdback released only after 12 months of proven uptime ≥98 %. IP indemnity must cover patent infringement damages unlimited in value—a non-negotiable term after recent $3·8 million lawsuit on auger-filler sensor tech. Finally, govern contract under Singapore International Arbitration Centre rules; median resolution time 8 months vs. 22 months in Chinese local courts, cutting legal cost exposure by ~60 %.
Site Commissioning: Zero Defect Start-Up
Mandate two vendor technicians on-site for ≥5 consecutive calendar days; daily rate capped at $450 all-in to prevent invoice creep. Tie the final 15 % payment to Site Acceptance Test (SAT) protocol mirroring FAT KPIs but run on buyer’s actual flour batch; any deviation >±0·5 % triggers root-cause analysis within 24 h. Require transfer of parameter recipe file in open XML format; lock PLC source code in escrow to safeguard against post-warranty vendor discontinuance. Close the loop with a digital OEE dashboard feeding SAP PM module; if 30-day rolling OEE <95 %, supplier must provide free-of-charge process engineer within 72 h or face $1 k per day penalty.
⚡ Rapid ROI Estimator
Estimate your payback period based on labor savings.
Estimated Payback: —
