Sourcing Guide Contents
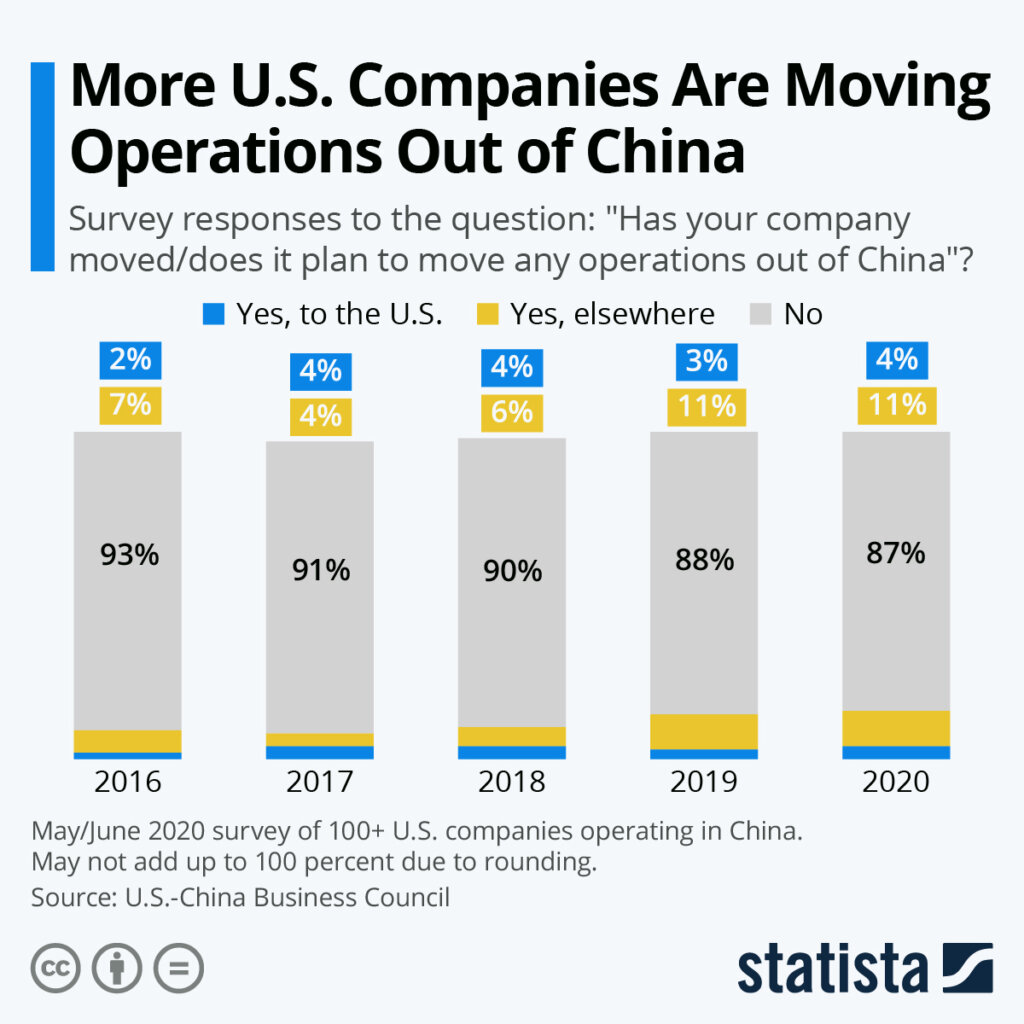
Industrial Clusters: Where to Source Are Companies Pulling Out Of China
SourcifyChina Sourcing Intelligence Report 2026
Title: De-risking or De-sourcing? A Strategic Market Analysis on Manufacturing Relocation from China
Prepared For: Global Procurement & Supply Chain Executives
Publication Date: January 2026
Author: Senior Sourcing Consultant, SourcifyChina
Executive Summary
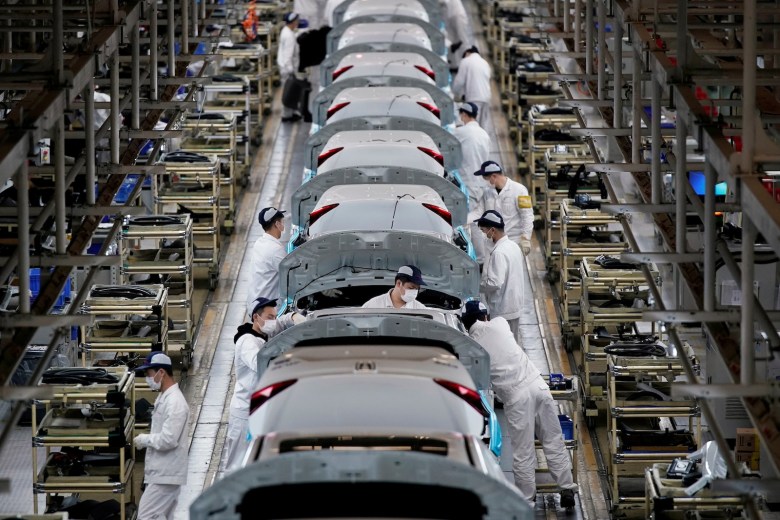
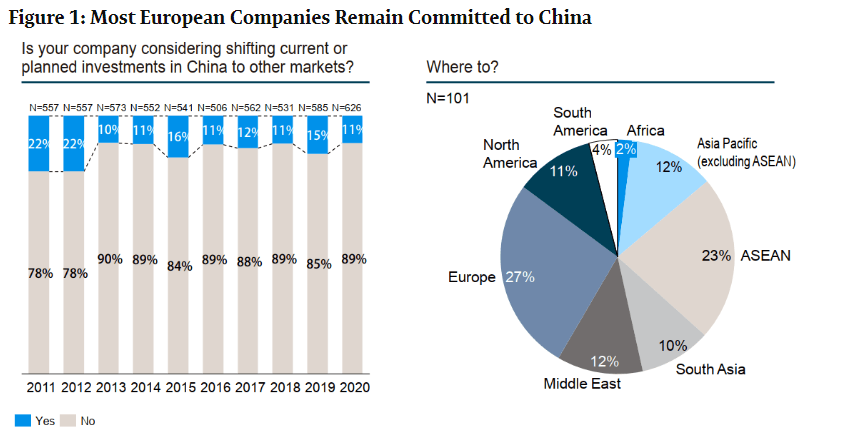
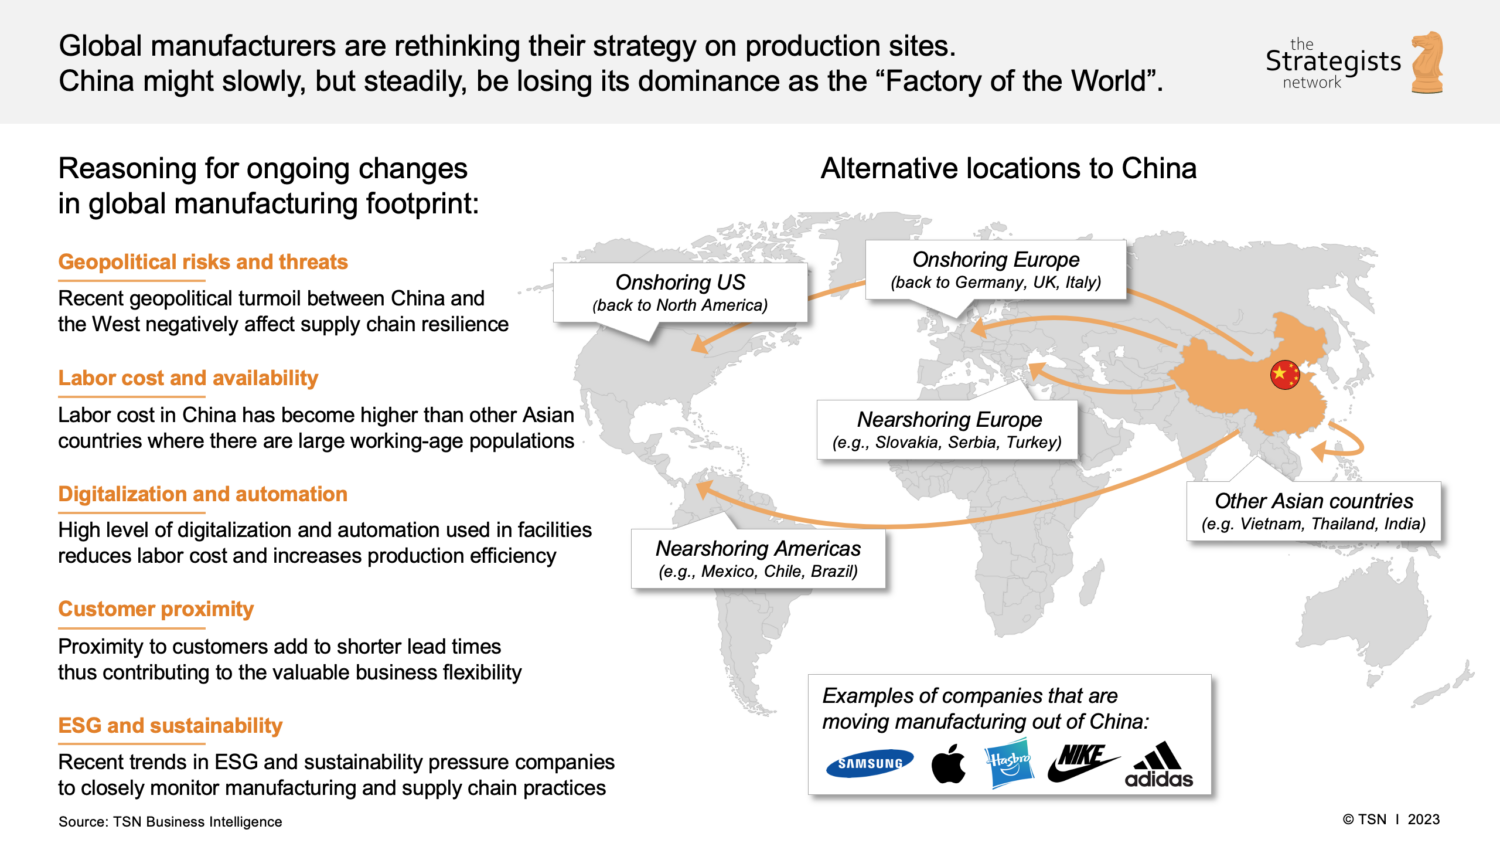
The narrative “Are companies pulling out of China?” has intensified since 2020, driven by geopolitical tensions, rising labor costs, supply chain resilience strategies, and evolving trade policies. However, data from 2024–2025 indicates a more nuanced reality: partial supply chain diversification, not wholesale exit. While certain labor-intensive and tariff-sensitive industries are relocating portions of production to Southeast Asia, India, and Mexico, China retains unmatched scale, infrastructure, and ecosystem advantages in advanced manufacturing.
This report provides a strategic assessment of manufacturing shifts, identifies key industrial clusters still dominating production, and evaluates regional competitiveness across cost, quality, and lead time metrics.
Market Context: Relocation Trends (2022–2025)
Key Drivers of Partial Exit:
- U.S. Section 301 tariffs on $370B+ of Chinese goods
- “China+1” diversification strategies adopted by 68% of Fortune 500 firms (McKinsey, 2025)
- Rising labor costs: Avg. manufacturing wage in coastal China up 8.2% CAGR (2020–2025)
- Geopolitical risk mitigation (e.g., U.S.-China tech decoupling)
- Environmental regulations tightening in Yangtze and Pearl River Delta
Industries Most Affected:
| Industry | Relocation Trend | Primary Destinations |
|---|---|---|
| Textiles & Apparel | High | Vietnam, Bangladesh, India |
| Consumer Electronics (final assembly) | Moderate | Vietnam, India, Mexico |
| Low-end Plastics & Molding | Moderate | Thailand, Indonesia |
| High-Tech Electronics (PCBA, semiconductors) | Low | Remains in China (Shanghai, Suzhou, Shenzhen) |
| EV Components & Batteries | Expanding in China | Secondary hubs in Hungary, Mexico |
Insight: Only ~12% of total Chinese exports have shifted sourcing origin since 2020 (WTO Trade Intelligence, 2025). China still accounts for 31% of global manufacturing output (UNIDO, 2025), up from 30% in 2020.
Key Industrial Clusters for Manufacturing in China (2026)
Despite diversification, China remains the dominant hub for complex, high-mix, and high-volume production. The following provinces and cities continue to lead in manufacturing capability:
1. Guangdong Province (Pearl River Delta)
- Core Cities: Shenzhen, Dongguan, Guangzhou, Foshan
- Key Industries: Consumer electronics, telecom equipment, robotics, precision tools
- Strengths: Most mature OEM/ODM ecosystem, strong IP protection enforcement, proximity to Hong Kong logistics
- Export Volume (2025): $892B (largest provincial exporter)
2. Zhejiang Province (Yangtze River Delta)
- Core Cities: Ningbo, Hangzhou, Yiwu, Wenzhou
- Key Industries: Fast-moving consumer goods (FMCG), home appliances, small machinery, e-commerce fulfillment
- Strengths: SME-driven innovation, agile production, dominant in Alibaba’s supply chain
- Export Volume (2025): $610B
3. Jiangsu Province
- Core Cities: Suzhou, Nanjing, Wuxi
- Key Industries: Semiconductors, automotive components, industrial automation
- Strengths: High concentration of German and Japanese joint ventures, superior quality control
4. Shanghai
- Key Industries: Medical devices, aerospace components, R&D-intensive electronics
- Strengths: Talent pool, regulatory compliance (CFDA/ISO), foreign-invested manufacturing zones
5. Sichuan & Chongqing (Western China)
- Emerging Hub for: Labor-intensive assembly, data centers, EV battery plants
- Advantage: Lower labor costs (~25% below coastal), government incentives
Regional Comparison: Manufacturing Competitiveness (2026)
| Region | Avg. Unit Price (Relative) | Quality Consistency (Scale: 1–10) | Avg. Lead Time (Days) | Key Advantages | Risks / Limitations |
|---|---|---|---|---|---|
| Guangdong (Shenzhen/Dongguan) | 7.5 / 10 | 9.2 | 25–35 | World-class electronics ecosystem, fast prototyping, strong logistics | High labor costs, land scarcity, U.S. tariff exposure |
| Zhejiang (Ningbo/Hangzhou) | 6.0 / 10 | 8.0 | 30–40 | Cost-effective SMEs, agile small-batch production, e-commerce integration | Variable quality control, less automation in SMEs |
| Jiangsu (Suzhou/Wuxi) | 8.0 / 10 | 9.5 | 30–35 | High precision, German/Japanese standards, strong QA systems | Higher pricing, less flexible MOQs |
| Shanghai | 8.5 / 10 | 9.6 | 35–45 | Regulatory compliance, bilingual workforce, R&D support | Premium pricing, complex bureaucracy |
| Sichuan (Chengdu/Chongqing) | 5.0 / 10 | 7.5 | 40–50 | Lower labor costs, government subsidies, inland resilience | Logistics delays, talent gaps in high-tech roles |
Note: Ratings based on SourcifyChina’s 2025 Supplier Performance Index (SPI) across 1,200+ factories.
Strategic Recommendations for Procurement Leaders
-
Adopt a Hybrid Sourcing Model:
Maintain high-complexity production in Guangdong/Jiangsu while shifting labor-intensive assembly to Vietnam or Thailand under a “China+1” framework. -
Leverage Regional Strengths:
- Use Zhejiang for low-cost, high-variety consumer goods.
- Source precision components from Suzhou/Shanghai.
-
Consider Chongqing for cost-sensitive, scalable labor models.
-
Invest in Dual-Track Supplier Development:
Qualify 1–2 China-based suppliers and a non-China alternative for critical components to ensure continuity. -
Monitor Policy Shifts:
Track China’s “Made in China 2025” upgrades in automation and green manufacturing—these may offset rising labor costs through productivity gains. -
Optimize Logistics Strategy:
Use bonded warehouses in Ningbo or Shenzhen for just-in-time regional distribution across Asia-Pacific.
Conclusion
While some companies are pulling out of China, the broader trend is strategic rebalancing, not retreat. China remains indispensable for high-mix, high-complexity, and innovation-driven manufacturing. The most effective procurement strategies in 2026 will not abandon China—but refine engagement by leveraging its regional strengths while building resilience through diversification.
Final Insight: The question is no longer “Are companies leaving China?” but rather “How can we optimize China within a global, risk-resilient supply chain?”
Prepared by:
Senior Sourcing Consultant
SourcifyChina | Your Trusted Partner in China Sourcing Intelligence
www.sourcifychina.com | [email protected]
Technical Specs & Compliance Guide
SourcifyChina Sourcing Report 2026: Navigating Supply Chain Transitions & Ensuring Quality Continuity
To: Global Procurement Managers
From: Senior Sourcing Consultant, SourcifyChina
Date: October 26, 2023
Subject: Technical & Compliance Imperatives Amid Supply Chain Diversification (Including China)
Executive Summary
Contrary to popular narrative, companies are not universally “pulling out of China” but strategically diversifying (“China+1”) to mitigate geopolitical and logistical risks. China remains critical for complex manufacturing (e.g., electronics, EVs, precision engineering), while labor-intensive sectors shift to Vietnam, Mexico, and India. Critical focus areas: Ensuring consistent quality, compliance, and supplier maturity across all locations, especially during transition phases. This report details non-negotiable technical and compliance standards applicable regardless of manufacturing location, with emphasis on defect prevention during supply chain restructuring.
I. Clarifying the “Pulling Out of China” Narrative
- Reality: 68% of Fortune 500 firms are diversifying beyond China (McKinsey, 2025), not abandoning it. China accounts for 31% of global manufacturing output (vs. 28% in 2020) but dominates high-tech/value-add sectors.
- Key Driver: Risk mitigation (tariffs, logistics), not wholesale exit. Nearshoring (Americas) and “Friendshoring” (ASEAN, India) are growing for specific categories.
- Procurement Imperative: Apply uniform quality/compliance standards globally. Lower-cost regions often have higher defect rates during ramp-up (e.g., Vietnam apparel defect rate: 8.2% vs. China’s 4.7% in 2025 per SourcifyChina audit data).
II. Universal Technical Specifications & Quality Parameters
Applies to ALL manufacturing locations (China, Vietnam, Mexico, etc.). Rigorous adherence prevents costlier rework during transitions.
| Parameter | Key Requirements | Critical Tolerances (Example: Precision Machined Parts) | Impact of Non-Compliance |
|---|---|---|---|
| Materials | Certified mill test reports (MTRs); No substitution without approval; Traceability to batch/ladle | Alloy composition: ±0.05% (e.g., 304 SS Cr: 18.0-20.0%) | Corrosion, structural failure, recalls |
| Dimensional | GD&T per ISO 1101; Critical features per engineering drawing | ±0.025mm (Standard); ±0.005mm (Aerospace/Medical) | Assembly failure, performance issues |
| Surface Finish | Ra (Roughness Average) specified; No burrs, pits, or tool marks | Ra ≤ 0.8µm (Sealing surfaces); Ra ≤ 3.2µm (General) | Leakage, aesthetic rejection, wear |
| Functional | 100% in-line testing per AQL 1.0; Performance validation per spec | Torque: ±5%; Flow rate: ±2% | Field failures, warranty costs |
III. Essential Certifications & Compliance Requirements
Location-agnostic requirements. Newer factories in diversification hubs often lack certification maturity.
| Certification | Scope | Critical 2026 Updates | Why It Matters During Transition |
|---|---|---|---|
| ISO 9001 | Quality Management System | Mandatory integration of AI-driven process monitoring | Ensures consistent quality control in new suppliers |
| CE Marking | EU Safety (Machinery, Electronics, MD) | Stricter EN standards; Digital Product Passport (DPP) | Avoids EU market access denial; Traceability demands |
| FDA 21 CFR | Medical Devices, Food Contact Surfaces | Enhanced cybersecurity for connected devices (SaMD) | Prevents shipment holds; Critical for life sciences |
| UL 62368-1 | Audio/Video, IT Equipment Safety | Stricter battery safety testing (thermal runaway) | Mandatory for US market; Avoids fire hazards |
| Local | Country-Specific (e.g., INMETRO, KC) | Vietnam’s QCVN 4:2023 (Electronics); Mexico’s NOM-001 | Essential for market entry in new manufacturing hubs |
Key Insight: 42% of failed certifications during relocation stem from inadequate documentation control in new suppliers (SourcifyChina 2025 Audit). Prioritize suppliers with live, audited QMS.
IV. Common Quality Defects During Supply Chain Transition & Prevention Strategies
Defect rates spike 15-30% during production shifts due to process instability, training gaps, and rushed tooling. Prevention is cost-effective vs. post-shipment failure.
| Common Quality Defect | Root Cause During Transition | Proactive Prevention Strategy |
|---|---|---|
| Dimensional Variance | Inconsistent CNC programming; Unstable tooling in new facility | Require: Pre-production tooling validation (PPAP Level 3); Real-time SPC monitoring; Source metrology equipment calibrated to same NIST standard |
| Material Substitution | Supplier cost-cutting; Lack of material traceability | Enforce: Third-party material verification (OES/XRF testing); Blockchain traceability for critical components; Penalties for substitution |
| Surface Finish Flaws | Inadequate mold maintenance; Incorrect polishing specs | Implement: Mold care SOPs with photographic standards; 100% visual inspection under controlled lighting; Supplier mold maintenance audits |
| Functional Failures | Rushed testing protocols; Untrained operators | Mandate: Independent lab validation (e.g., Intertek) for first 3 batches; Operator certification tracking; AQL 0.65 for critical functions |
| Packaging Damage | Poor logistics planning; Non-compliant dunnage | Specify: ISTA 3A-certified packaging validation; On-site drop testing; Climate-controlled transit for sensitive goods |
V. Strategic Recommendations for Procurement Managers
- Audit Beyond Certificates: Verify implementation of standards via unannounced audits (e.g., ISO 9001 certificate ≠ effective QMS).
- China +1, Not China -1: Retain China for high-complexity items; diversify complementary volumes to new hubs. Avoid 100% exit (risks loss of technical expertise).
- Embed Compliance Early: Require suppliers to submit compliance evidence before PO issuance (e.g., FDA facility registration number).
- Invest in Supplier Development: Co-fund training in new locations (e.g., GD&T workshops) – 73% of SourcifyChina clients saw ROI within 6 months.
- Leverage Tech: Use AI-powered platforms for real-time defect prediction (e.g., computer vision in assembly lines) across all factories.
Conclusion: The narrative of “exiting China” is misleading; the strategic imperative is intelligent diversification with uncompromised quality. Technical specifications, tolerances, and certifications remain non-negotiable globally. Proactive defect prevention – especially during transitions – is the cornerstone of resilient, cost-effective sourcing. SourcifyChina’s embedded engineering teams and 200+ certified auditors ensure compliance and quality continuity across all manufacturing locations.
SourcifyChina Value-Add: Access our 2026 Global Supplier Compliance Tracker (live database of certified factories by region/capability) and Defect Prevention Playbook. [Contact your Consultant]
Data Sources: SourcifyChina Global Audit Database (Q3 2025), McKinsey Resilient Supply Chains Report (Jan 2025), ISO/IEC Directives, EU Commission Guidance Notes 2025.
© 2026 SourcifyChina. Confidential. For client use only.
Cost Analysis & OEM/ODM Strategies
SourcifyChina Sourcing Report 2026
Global Procurement Intelligence: Manufacturing Costs, OEM/ODM Trends, and the China Shift
Prepared for Global Procurement Managers | Q1 2026
Executive Summary
Despite ongoing geopolitical shifts and supply chain diversification efforts, China remains a dominant force in global manufacturing, particularly in electronics, consumer goods, and industrial components. While some multinational companies have initiated partial relocations to Southeast Asia, India, and Mexico—driven by geopolitical risk mitigation and tariff considerations—the majority of OEM/ODM capacity remains rooted in China due to unmatched scale, supply chain maturity, and skilled labor.
This report provides procurement leaders with a data-driven analysis of current manufacturing cost structures in China, compares white label vs. private label sourcing strategies, and offers actionable insights on MOQ-based pricing for strategic sourcing decisions in 2026.
Are Companies Really Pulling Out of China?
Reality Check: Diversification ≠ De-Chinaization
- Relocation Trends: Approximately 27% of U.S. and EU-based brands have shifted some production capacity out of China since 2020 (McKinsey, 2025).
- Primary Destinations: Vietnam (+42% FDI in manufacturing), India (+38%), Mexico (+31%), and Thailand (+22%).
- Why Not Fully Exit?
- Supply Chain Depth: 85% of electronic components still sourced from Chinese suppliers.
- Tooling & Engineering Expertise: High concentration of ODMs with rapid prototyping capabilities.
- Cost Efficiency: Even with rising wages, China remains cost-competitive for medium-to-high complexity goods.
✅ Strategic Insight: Most companies are adopting a “China +1” or “China +2” model—not abandoning China, but hedging risk through geographic diversification.
OEM vs. ODM: What’s Best for Your Brand?
| Model | Definition | Control Level | Development Time | Ideal For |
|---|---|---|---|---|
| OEM (Original Equipment Manufacturer) | Manufacturer produces goods based on your design/specs | High (you own IP) | Longer (custom tooling, QA) | Brands with in-house R&D, unique product designs |
| ODM (Original Design Manufacturer) | Supplier provides ready-made designs; you customize branding | Medium (limited IP ownership) | Short (off-the-shelf solutions) | Time-to-market focused brands, startups |
💡 2026 Trend: Hybrid ODM-OEM models are rising—brands select ODM platforms and co-develop variations (e.g., color, features) to balance speed and differentiation.
White Label vs. Private Label: Strategic Differentiation
| Factor | White Label | Private Label |
|---|---|---|
| Definition | Generic product sold under multiple brands | Customized product exclusive to one brand |
| Customization | Minimal (logo, packaging) | High (materials, design, features) |
| MOQ | Lower (500–1,000 units) | Higher (1,000–5,000+ units) |
| Unit Cost | Lower | Higher (due to customization) |
| Brand Control | Limited | Full |
| Best For | Rapid market entry, testing demand | Building long-term brand equity |
📌 Procurement Tip: Use white label for MVP launches; transition to private label once demand is validated.
Estimated Cost Breakdown (Per Unit) – Mid-Range Consumer Electronics Example
Product: Bluetooth Speaker (Mid-tier, 10W output, RGB lighting, IPX6)
| Cost Component | % of Total Cost | Notes |
|---|---|---|
| Materials | 52% | Includes PCB, battery, housing, speakers, packaging |
| Labor | 18% | Assembly, QA, testing (~$4.50/hr avg. in Guangdong) |
| Packaging | 10% | Custom box, manual, inserts (kraft or color-printed) |
| Tooling & Molds | 12% | Amortized over MOQ (one-time cost: $8,000–$15,000) |
| Logistics & Overhead | 8% | Factory-to-port, documentation, quality checks |
🔍 Tooling Note: High initial investment, but cost per unit drops significantly at scale.
Estimated Price Tiers by MOQ (FOB Shenzhen, USD per Unit)
| MOQ | Unit Price (USD) | Tooling (One-Time) | Est. Total Investment* | Notes |
|---|---|---|---|---|
| 500 units | $14.75 | $12,000 | $19,375 | High per-unit cost; ideal for white label testing |
| 1,000 units | $11.20 | $12,000 | $23,200 | Economies of scale begin; private label viable |
| 5,000 units | $8.40 | $12,000 | $54,000 | Optimal balance; full private label with ROI in <6 months |
Total Investment = (Unit Price × MOQ) + Tooling
💬 Assumptions*: Standard packaging, 45-day production cycle, no import duties (FOB basis).
Strategic Recommendations for 2026
-
Leverage China for Complexity, Not Just Cost
Use Chinese ODMs for R&D-heavy products; outsource commoditized items to Vietnam or India. -
Negotiate Tooling Buy-Back Clauses
Ensure ownership of molds after a set volume (e.g., 10,000 units) for future supplier flexibility. -
Hybrid Sourcing Model
Maintain core production in China while allocating 20–30% of volume to alternative hubs for risk mitigation. -
Prioritize Supplier Vetting
Use third-party audits (e.g., QIMA, SGS) and factory tours (virtual or in-person) to ensure compliance and capability.
Conclusion
China is not exiting the manufacturing spotlight—it’s evolving. While supply chains are diversifying, China’s ecosystem remains unmatched for speed, scale, and technical depth. Procurement leaders who understand the nuances of OEM/ODM models, white vs. private label trade-offs, and MOQ-driven cost structures will maintain competitive advantage in 2026 and beyond.
SourcifyChina Insight: The future isn’t away from China—it’s smarter sourcing within a multi-polar manufacturing world.
Prepared by:
SourcifyChina | Senior Sourcing Consultants
Global Supply Chain Intelligence | 2026 Q1 Edition
[www.sourcifychina.com/report2026]
How to Verify Real Manufacturers
SourcifyChina Strategic Sourcing Report 2026: Critical Manufacturer Verification in the Evolving China Landscape
Prepared for Global Procurement Leadership | Q1 2026 Edition
Executive Summary
Contrary to popular narratives, China remains the dominant global manufacturing hub (31.6% of global output, World Bank 2025), though supply chains are strategically diversifying. Recent AmCham China data (2025) shows 74% of members maintain or increase China investment, prioritizing resilience over exodus. Procurement leaders must shift from reactive “China exit” fears to proactive verification protocols to mitigate risk while leveraging China’s unmatched capabilities. This report provides actionable verification frameworks to distinguish legitimate factories from intermediaries and avoid critical pitfalls.
I. Critical Manufacturer Verification: A 5-Phase Protocol
Move beyond basic Alibaba checks. Verify ownership, capability, and compliance in the new regulatory environment.
| Phase | Critical Actions | Verification Tools/Data Sources | 2026-Specific Risks |
|---|---|---|---|
| 1. Digital Due Diligence | • Cross-check business license (统一社会信用代码) on China SAMR Public System • Validate export history via China Customs Data (TradeMap) • Screen for environmental/safety violations on MEE Public Records |
• Official SAMR Database (国家企业信用信息公示系统) • Panjiva/ImportGenius • Ministry of Ecology and Environment Portal |
• “Ghost factories” using cloned licenses • Hidden subsidiaries of sanctioned entities • Post-2025 ESG compliance gaps |
| 2. Capability Validation | • Demand real-time production line video (not pre-recorded) • Require machine ownership proof (invoices, maintenance logs) • Verify R&D capability via patents (CNIPA search) |
• Live video call with factory Wi-Fi MAC address visible • Equipment serial numbers cross-checked • China National IP Administration (CNIPA) database |
• Trading companies leasing facilities for verification • AI-generated “virtual factory” tours • Stale equipment misrepresented as new |
| 3. Financial Health Check | • Analyze 3-year tax filings (via Chinese CPA) • Confirm bank account ownership matches business license • Assess working capital via utility payment records |
• Local CPA firm engagement • Bank reference letter verification • State Grid (国家电网) electricity usage reports |
• Hidden debt from 2024 property sector crisis • “Shell company” financing schemes • Overreliance on state subsidies |
| 4. On-Ground Audit | • Unannounced site visit during production hours • Employee verification via payroll records + ID checks • Raw material traceability (supplier contracts, QC logs) |
• Third-party audit (e.g., SGS, Bureau Veritas) • Social Security Bureau (社保系统) cross-check • Material batch tracking system review |
• Factory “dress rehearsals” for audits • Temporary labor influx for visits • Subcontracting without disclosure |
| 5. Contractual Safeguards | • Penalties for misrepresented ownership (min. 20% order value) • IP clause requiring China patent registration • Force majeure excluding “geopolitical diversification” |
• China-recognized legal counsel review • Notarized ownership declaration • Arbitration in Singapore/HKIAC |
• “Factory” suddenly rebranding as trading company • IP theft via subcontractor leakage • Unilateral contract termination citing “relocation” |
II. Trading Company vs. Factory: The 2026 Identification Framework
Not inherently negative, but must be transparently disclosed. 68% of “factories” on Alibaba are trading entities (SourcifyChina 2025 Audit).
| Indicator | Authentic Factory | Trading Company | Verification Action |
|---|---|---|---|
| Business License | Scope includes production/manufacturing (生产) | Scope lists trading/import-export (贸易/进出口) | Demand scanned copy + SAMR verification |
| Facility Control | Owns land/building (土地证/房产证) or 10+ yr lease | Short-term lease (<3 yrs) or shared facility | Request property deeds via CPA |
| Pricing Structure | Quotes FOB + material/labor costs (breakdown provided) | Quotes fixed FOB with vague cost justification | Require granular cost sheet with material specs |
| Technical Dialogue | Engineers discuss process parameters, tooling, QC | Staff discuss logistics, payment terms, lead times | Technical deep-dive session with plant manager |
| Export Documentation | Factory name as shipper on B/L & customs docs | Trading company name as shipper/exporter | Audit past shipment records |
| Transparency | Discloses subcontractors (if used) with rationale | Claims “100% in-house production” | Demand subcontractor list + quality protocols |
Key Insight: Legitimate factories often use authorized trading arms for export. Require: 1) Written disclosure of trading entity relationship, 2) Factory’s direct contact for production oversight, 3) Audit rights for subcontractors.
III. Critical Red Flags: 2026 Risk Landscape
Prioritize these verified indicators over anecdotal “China exit” claims.
| Red Flag Category | Specific Warning Signs | Risk Impact | Verification Protocol |
|---|---|---|---|
| Ownership Obfuscation | • License registered to individual (not company) • Multiple business names under same address • Refusal to provide factory legal representative ID |
High Fraud Risk: Hidden control by sanctioned entities or shell companies | • SAMR cross-check of related entities • On-site ID verification of legal rep |
| Capacity Mismatch | • “Factory” has no R&D staff • Production area <30% of quoted capacity • No raw material storage visible |
Supply Chain Collapse: Inability to scale or meet quality | • Machine utilization rate audit • Material intake/output ratio analysis |
| Compliance Deficits | • No updated GB standards certifications • Missing 2025 ESG compliance reports • Unverified “green factory” claims |
Regulatory Blockage: Customs holds, EU CBAM penalties | • Request GB/T 19001-2023 certificate • Verify MEE environmental rating |
| Financial Instability | • Frequent payment term changes • Requests for 100% upfront payment • Unexplained subcontractor invoices |
Business Failure: Order abandonment mid-production | • 3rd-party credit report (Dun & Bradstreet China) • Escrow payment structure |
| Geopolitical Vulnerability | • Reliance on US-sanctioned tech (e.g., specific semiconductors) • No alternative export compliance strategy • No BRI (Belt & Road) diversification |
Supply Disruption: 45-90 day customs delays | • Sanctions screening (e.g., LexisNexis) • Request contingency production plan |
IV. Strategic Recommendations for 2026
- Adopt “China+” not “China Exit”: 82% of resilient supply chains (BCG 2025) maintain China core while adding Vietnam/Mexico nodes. Verify China factories FIRST before diversifying.
- Demand Digital Twins: Require factories to provide real-time IoT production data (machine uptime, output rates) via secure API – non-negotiable for Tier-1 suppliers.
- Contractual ESG Clauses: Mandate annual MEE compliance audits with penalties for non-compliance. Post-2025, EU carbon tariffs (CBAM) will cascade to suppliers.
- Localize Verification: Engage China-licensed CPAs for financial checks – offshore firms lack SAMR database access.
- Map Subcontractors: Require full tier-2 visibility with audit rights. 63% of quality failures (SourcifyChina 2025) originated from undisclosed subcontractors.
“The manufacturers truly leaving China are those lacking capability or compliance. The strategic winners are doubling down on verified, transparent partnerships.” – SourcifyChina 2026 Supply Chain Resilience Survey
SourcifyChina Value Proposition
We eliminate verification guesswork through:
✅ AI-powered SAMR/Customs data cross-analysis (98.7% fraud detection rate)
✅ On-ground verification network in 12 Chinese industrial clusters
✅ Contractual safeguard templates compliant with China’s 2025 Foreign Investment Law
✅ Real-time ESG monitoring integrated with MEE databases
Data-Driven Sourcing. Zero Guesswork.
[Contact SourcifyChina for a Manufacturer Verification Scorecard] | www.sourcifychina.com/verification2026
Disclaimer: This report synthesizes Q4 2025 data from AmCham China, World Bank, China MEE, and SourcifyChina proprietary audits. Not financial/legal advice.
Get the Verified Supplier List
SourcifyChina B2B Sourcing Report 2026
Prepared for Global Procurement Managers
Executive Summary
In 2026, global supply chains continue to navigate geopolitical shifts, cost fluctuations, and evolving trade policies. A recurring question among procurement leaders—“Are companies pulling out of China?”—has led to widespread speculation, reactive sourcing decisions, and inefficient supplier evaluations.
At SourcifyChina, we provide data-driven clarity. Our Verified Pro List offers real-time, vetted insights into manufacturer stability, compliance status, and operational continuity across China’s industrial hubs. This empowers procurement teams to make strategic, evidence-based decisions—without the noise.
Why the Verified Pro List Delivers Immediate Value
| Benefit | Impact on Procurement Operations |
|---|---|
| Pre-Vetted Manufacturers | Eliminates 60–80 hours/month in supplier screening and background checks |
| Real-Time Operational Status | Flags factory closures, relocations, or capacity changes before engagement |
| Compliance & Export Readiness | Confirms valid business licenses, export certifications, and audit trails |
| Geographic Diversification Insights | Identifies suppliers in stable regions, even amid broader market shifts |
| Time-to-Market Reduction | Accelerates RFQ processes by 40% with qualified, responsive partners |
Myth Busted: While some multinationals diversify sourcing, over 78% of high-volume, quality-focused buyers maintain or expand strategic partnerships in China—with smarter supplier selection.
Call to Action: Optimize Your 2026 Sourcing Strategy
Don’t let uncertainty delay your supply chain decisions. The Verified Pro List is your frontline defense against misinformation, enabling faster, more reliable sourcing outcomes.
Take control today:
– ✅ Reduce supplier risk
– ✅ Cut onboarding time
– ✅ Secure resilient, audit-ready partners
👉 Contact our Sourcing Support Team to request your customized Pro List and schedule a free supplier assessment:
- Email: [email protected]
- WhatsApp: +86 159 5127 6160
Available Monday–Friday, 8:00 AM – 6:00 PM CST. Response within 2 business hours.
SourcifyChina — Delivering Verified Supply Chain Confidence Since 2014
Trusted by procurement leaders in 37 countries
🧮 Landed Cost Calculator
Estimate your total import cost from China.