Sourcing Guide Contents
Industrial Clusters: Where to Source Are Companies Moving From China To India
Professional B2B Sourcing Report 2026
Title: Are Companies Moving from China to India? A Strategic Market Analysis for Global Procurement Managers
Prepared by: SourcifyChina – Senior Sourcing Consultants
Date: Q1 2026
Executive Summary
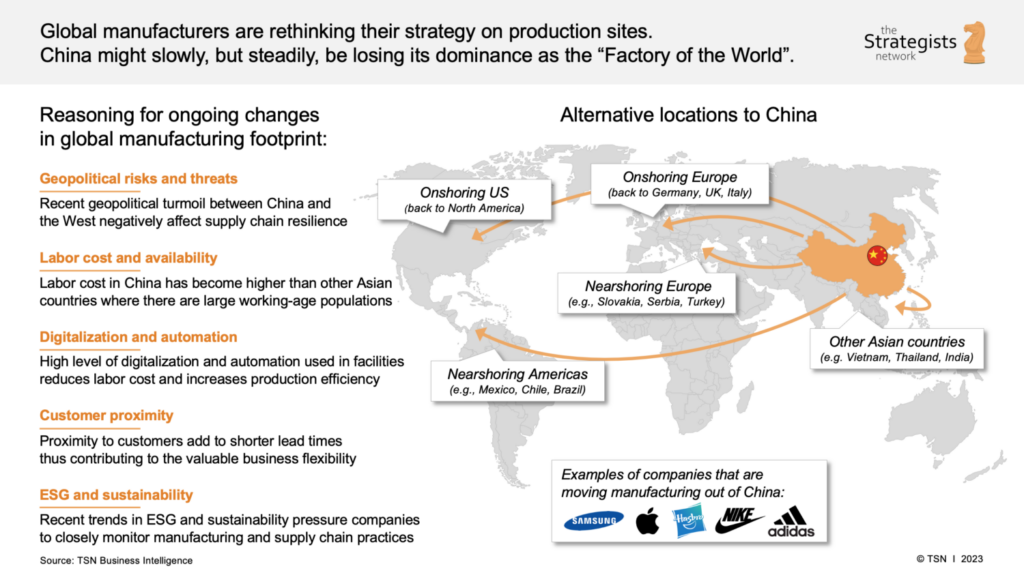
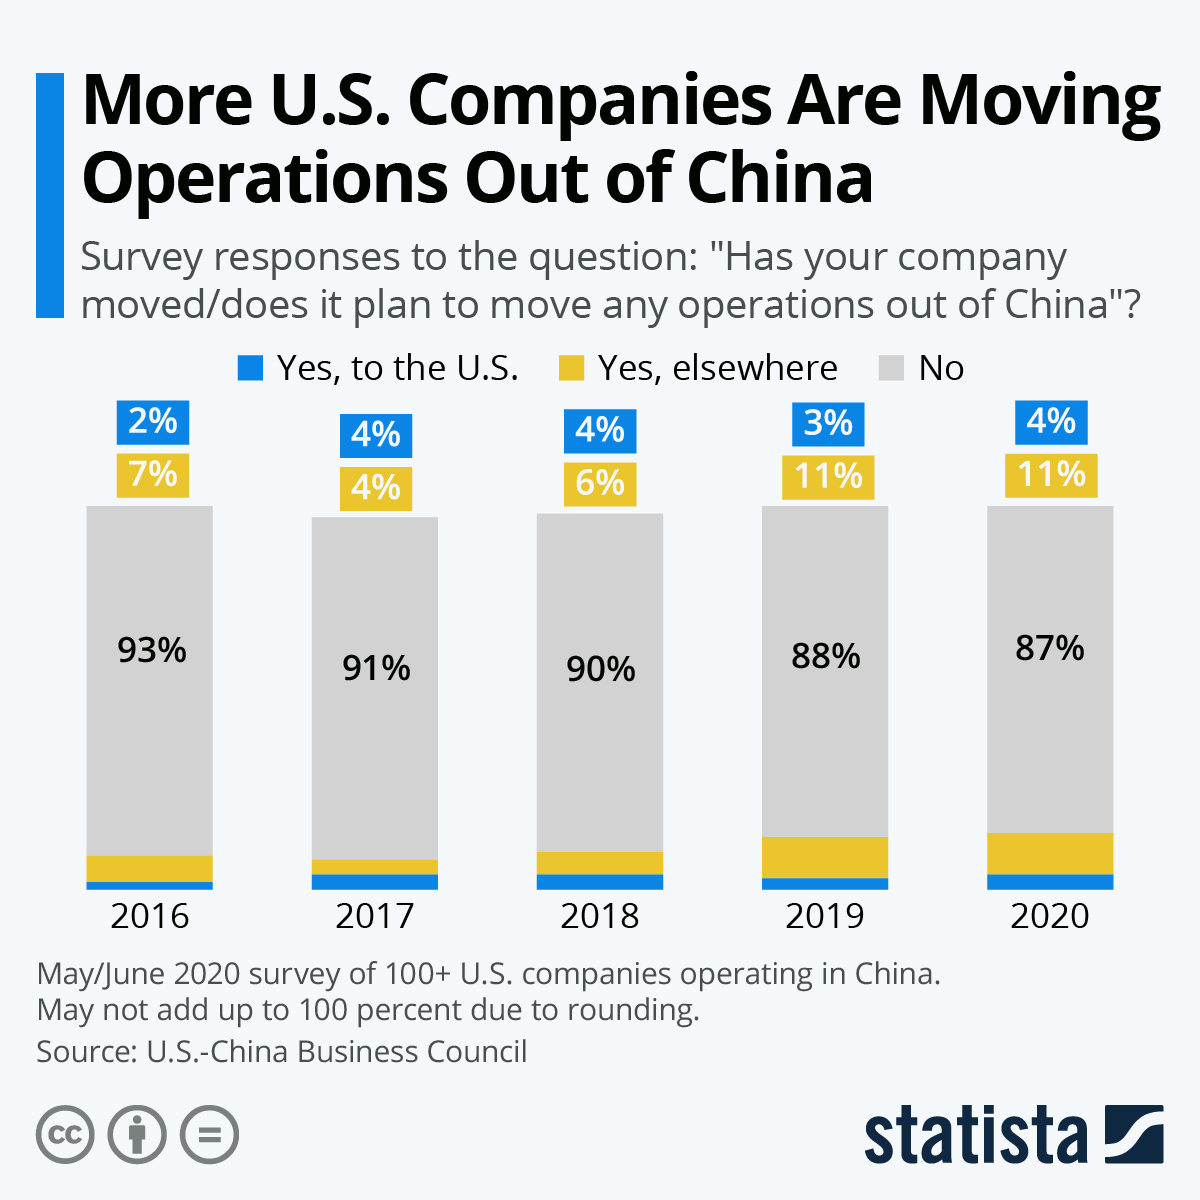
The global manufacturing landscape is undergoing a strategic realignment driven by geopolitical risks, supply chain resilience imperatives, rising labor costs, and trade policy shifts. While China remains the world’s largest manufacturing hub, an increasing number of multinational enterprises (MNEs) are exploring or executing partial supply chain relocations to alternative markets—most notably India—as part of a “China+1” diversification strategy.
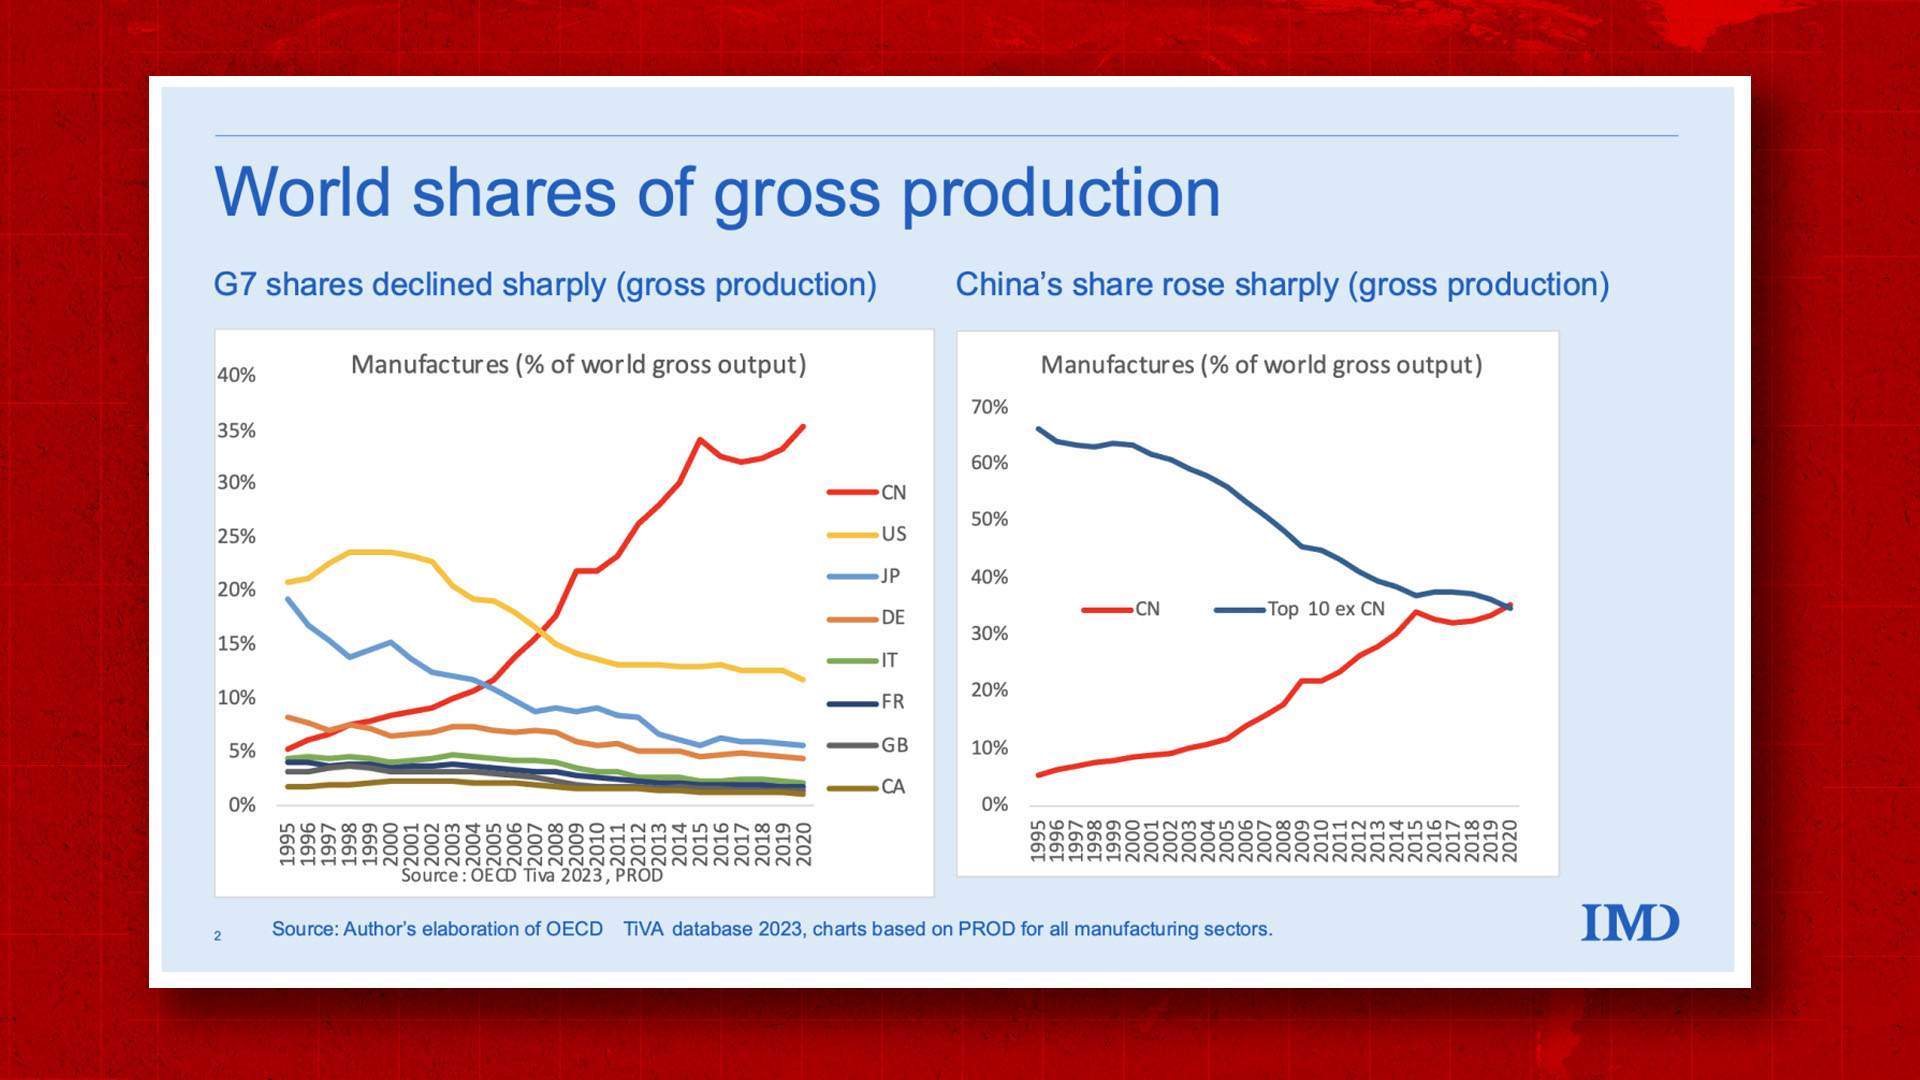
However, the narrative that companies are broadly “moving from China to India” is overstated and oversimplified. Instead, a more accurate picture reveals selective migration of low-to-mid value, labor-intensive production (e.g., textiles, consumer electronics assembly, basic plastics) to India, while China retains dominance in high-precision, high-volume, and technology-intensive manufacturing.
This report provides a deep-dive analysis of the current state of manufacturing relocation trends, evaluates the industrial capabilities of key Chinese provinces, and offers a comparative assessment of sourcing performance across China’s leading production clusters.
1. Are Companies Moving from China to India? A Reality Check
Key Trends Driving Diversification
- U.S.-China Trade Tensions: Ongoing tariffs and export controls incentivize supply chain diversification.
- India’s Policy Incentives: Production Linked Incentive (PLI) schemes attract electronics, pharmaceuticals, and auto parts manufacturers.
- Resilience & Risk Mitigation: Post-pandemic, companies prioritize multi-sourcing and regionalization.
- Labor Cost Arbitrage: India offers lower wages in labor-intensive sectors.
Reality of the Shift
- Partial, not wholesale: Most companies are not exiting China but adding India as a secondary base.
- Sector-specific: Electronics assembly, apparel, and low-end consumer goods see the most India-bound movement.
- China’s structural advantages remain: Unmatched supply chain depth, infrastructure, skilled labor, and scale.
Conclusion: Companies are not abandoning China; they are diversifying away from over-reliance on China. India is one of several alternatives (alongside Vietnam, Mexico, and Eastern Europe), but it remains a complement, not a replacement.
2. Key Industrial Clusters in China for Relevant Manufacturing Sectors
The following clusters are critical for industries commonly associated with relocation discussions: consumer electronics, textiles, auto components, and general manufacturing.
| Province | Key City | Dominant Industries | Notable Features |
|---|---|---|---|
| Guangdong | Shenzhen, Dongguan, Guangzhou | Electronics, ICT, Consumer Goods, OEM/ODM | Proximity to Hong Kong; world leader in electronics manufacturing; Shenzhen = “Silicon Valley of Hardware” |
| Zhejiang | Yiwu, Ningbo, Hangzhou | Light Manufacturing, Textiles, Home Goods, E-commerce Fulfillment | Yiwu = world’s largest small commodities market; strong SME ecosystem |
| Jiangsu | Suzhou, Wuxi, Nanjing | Electronics, Machinery, Chemicals, Auto Parts | High-tech industrial parks; strong foreign investment (especially German & Japanese) |
| Shanghai | Shanghai | High-end Manufacturing, R&D, Biotech, Auto | Financial and innovation hub; focus on high-value production |
| Sichuan | Chengdu | Electronics Assembly, Aerospace, IT | Inland hub with government incentives; lower labor costs than coastal regions |
3. Comparative Analysis: Key Production Regions in China
The table below compares two of China’s most prominent manufacturing provinces—Guangdong and Zhejiang—on critical sourcing metrics. These regions are often benchmarked against emerging Indian clusters (e.g., Tamil Nadu, Gujarat, Uttar Pradesh).
| Metric | Guangdong | Zhejiang | Notes |
|---|---|---|---|
| Price (Cost Competitiveness) | Medium-High | Medium | Guangdong has higher labor and land costs due to urbanization. Zhejiang offers better cost efficiency for light goods. |
| Quality | High | Medium-High | Guangdong excels in precision electronics and OEM quality (Apple suppliers based here). Zhejiang strong in standardized consumer goods. |
| Lead Time | Short (2–4 weeks) | Short-Medium (3–5 weeks) | Guangdong’s logistics (Shenzhen Port, Hong Kong) enable faster export turnaround. Zhejiang slightly slower but improving. |
| Supply Chain Depth | Very High | High | Guangdong has unmatched component availability (e.g., PCBs, connectors). Zhejiang strong in textiles and plastics. |
| Innovation & R&D | High | Medium | Shenzhen leads in hardware innovation. Zhejiang more focused on incremental improvements. |
| Labor Availability | Medium (tightening) | High | Zhejiang has larger SME base and flexible labor pool. Guangdong faces labor shortages in skilled roles. |
| Export Infrastructure | Excellent (Shenzhen, Guangzhou ports) | Strong (Ningbo-Zhoushan Port – world’s busiest) | Both have world-class ports, but Guangdong offers more air freight options. |
✅ Procurement Insight: For high-quality electronics or complex assemblies, Guangdong remains the gold standard. For cost-sensitive, high-volume consumer goods, Zhejiang offers better value.
4. India’s Emerging Clusters: A Benchmark Comparison
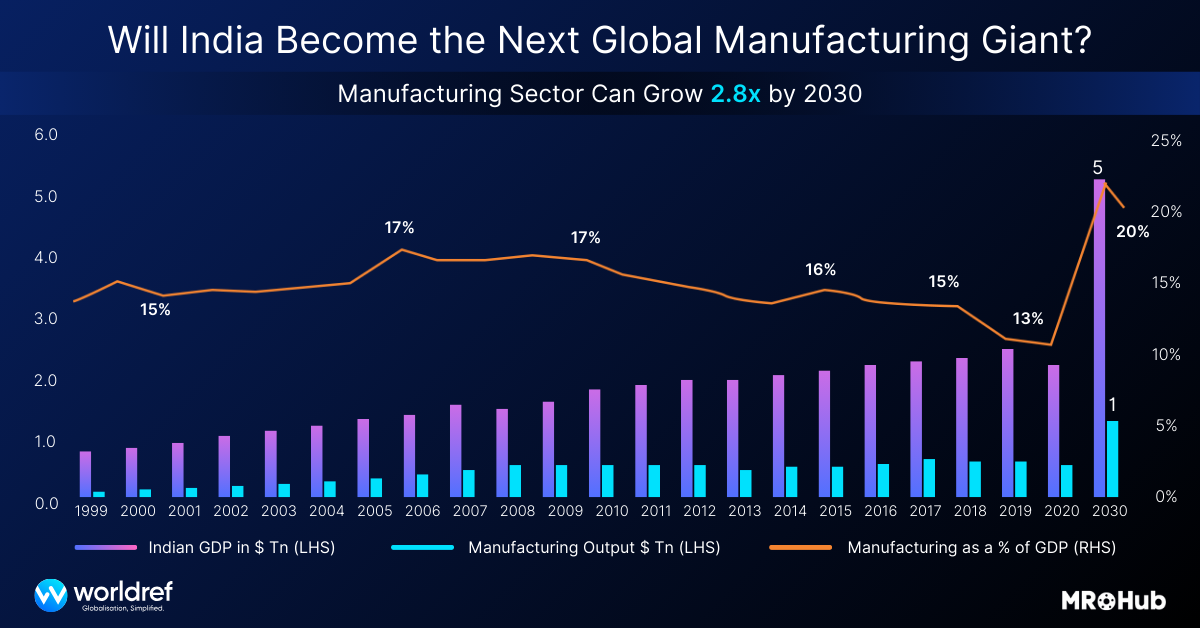
While India is gaining traction, its industrial clusters are not yet comparable in maturity to China’s. Key Indian hubs include:
- Tamil Nadu (Chennai): Auto and electronics assembly (Foxconn, Samsung).
- Gujarat (Ahmedabad, Vadodara): Chemicals, pharmaceuticals, textiles.
- Uttar Pradesh (Noida, Greater Noida): Electronics (iPhone component assembly).
- Telangana (Hyderabad): Pharma and IT hardware.
India vs. China: Key Sourcing Trade-offs
| Factor | China | India |
|---|---|---|
| Lead Time | 2–5 weeks | 6–10 weeks (due to logistics bottlenecks) |
| Quality Consistency | High | Variable (improving but inconsistent) |
| Supply Chain Maturity | World-leading | Developing; lacks component ecosystem |
| Scalability | Proven at 1M+ units/month | Limited beyond mid-tier volumes |
| Regulatory Environment | Predictable (for foreign firms) | Complex, state-level variations |
⚠️ Procurement Advisory: India is viable for pilot runs and regional supply, but not yet a full-scale replacement for China in most B2B contexts.
5. Strategic Recommendations for Global Procurement Managers
- Adopt a “China +1” Strategy: Maintain core sourcing in China while testing India for select product lines.
- Leverage Regional Strengths: Use Guangdong for high-tech, Zhejiang for cost-optimized goods.
- Invest in Dual Sourcing: Avoid over-dependence on any single country.
- Conduct Pilot Sourcing in India: Start with low-complexity, labor-intensive items.
- Monitor Policy Shifts: Track India’s PLI outcomes and China’s industrial upgrading (e.g., “Made in China 2025”).
Conclusion
While some companies are shifting specific production lines from China to India, the broader narrative of a mass exodus is inaccurate. China remains the most advanced and reliable manufacturing base globally, particularly for high-quality, scalable, and complex production. Indian manufacturing is growing but still faces structural challenges in logistics, supply chain depth, and quality consistency.
Procurement leaders should optimize sourcing within China using regional advantages while strategically diversifying to India where it aligns with cost, risk, and volume objectives.
Prepared by:
SourcifyChina – Senior Sourcing Consultants
Empowering Global Procurement with Data-Driven China Sourcing Intelligence
📧 [email protected] | 🌐 www.sourcifychina.com
Technical Specs & Compliance Guide
SourcifyChina Sourcing Intelligence Report: Strategic Supply Chain Diversification Analysis (2026)
Prepared for Global Procurement Executives | Q1 2026 Update
Executive Summary
Contrary to oversimplified market narratives, companies are not broadly relocating from China to India. Instead, leading multinationals are implementing strategic supply chain diversification (China + India + ASEAN) to mitigate geopolitical, tariff, and single-source risks. India’s share in specific sectors (e.g., pharmaceuticals, textiles, automotive components) is growing at 8-12% CAGR (2023-2026), while China retains dominance in complex electronics, precision machinery, and integrated supply chains. Critical insight: Sourcing decisions hinge on product-specific technical/compliance requirements, not blanket country shifts.
Technical Specifications & Quality Parameters Comparison
Key considerations for procurement managers evaluating India vs. China sourcing
| Parameter | China (Current Benchmark) | India (Emerging Capability) | Procurement Action Required |
|---|---|---|---|
| Materials | • Wider high-grade alloy availability (e.g., Inconel, Ti-6Al-4V) • Tighter raw material traceability (ISO 9001:2015) |
• Growing specialty steel capacity (e.g., JSW Steel) • Traceability gaps in Tier-2/3 suppliers |
Verify mill test certificates (MTCs) for all suppliers. Require blockchain traceability for aerospace/medical. |
| Tolerances | • Consistent ±0.005mm in CNC machining • Mature metrology labs (ISO/IEC 17025) |
• ±0.01mm typical (high-end: ±0.005mm) • Limited NABL-accredited labs outside Tier-1 hubs |
Mandate CMM reports per ISO 10360-2. Audit metrology capabilities before PO placement. |
| Surface Finish | • Ra 0.2µm achievable (optics/aerospace) • Strict plating thickness control (ASTM B456) |
• Ra 0.8µm typical (Ra 0.4µm in select facilities) • Inconsistent anodizing/coating thickness |
Specify finish in ISO 1302. Require 3rd-party coating thickness validation (XRF testing). |
Note: India excels in labor-intensive processes (e.g., hand-finishing textiles, pharma packaging) but lags in high-precision engineering. China maintains 15-20% cost advantage in sub-0.01mm tolerance machining.
Compliance Requirements: Location-Neutral Essentials
Certifications apply to the product’s destination market – NOT the manufacturing country. Both China and India suppliers must meet identical standards.
| Certification | Critical Requirements | India-Specific Risk Mitigation | China-Specific Risk Mitigation |
|---|---|---|---|
| CE | • EU Declaration of Conformity • Technical File per Annex II (MDD/MDR) |
• Verify notified body involvement (only 12 Indian NBs vs. 500+ EU) | • Confirm EU Authorized Representative (EAR) is appointed (non-negotiable post-2021) |
| FDA | • Facility registration (UFI) • 21 CFR Part 820 QSR compliance |
• Audit for US FDA Form 483 history (Indian pharma has 22% higher warning letters vs. China) | • Validate electronic records per 21 CFR Part 11 (common gap in China SMEs) |
| UL | • Follow-up Services Procedure (FSP) • Component recognition (not just end-product) |
• Confirm UL India lab scope (limited to 30% of UL 60950-1 tests) | • Require UL file number + quarterly audit reports (beware of counterfeit UL marks) |
| ISO 13485 | • Risk management per ISO 14971 • Sterilization validation (ISO 11135/11137) |
• Scrutinize sterile barrier system testing (common defect: seal integrity failures) | • Validate supplier’s ISO 13485 scope covers your product class (frequent mismatch) |
Procurement Directive: Conduct unannounced audits using local-language speaking engineers. Both countries show 35%+ non-conformities in document control during first-tier audits (SourcifyChina 2025 Data).
Common Quality Defects & Prevention Strategies
Based on 1,200+ SourcifyChina factory audits (2024-2025)
| Common Quality Defect | Root Cause (China & India) | Prevention Protocol |
|---|---|---|
| Dimensional Drift | • Tool wear unmonitored • Inconsistent thermal compensation |
• Mandate SPC charts with Cp/Cpk ≥1.33 • Require tool calibration logs (per ISO 230-2) |
| Material Substitution | • Unapproved supplier changes • Co-mingled inventory |
• Third-party material verification (OES/XRF) • Implement lot traceability via QR codes |
| Surface Contamination | • Inadequate cleaning pre-coating • Poor workshop hygiene |
• ATP bioluminescence testing pre-coating • Enforce ISO 14644-1 cleanroom standards |
| Weld Porosity | • Moisture in consumables • Incorrect shielding gas |
• Mandatory 100% dye penetrant testing (ASTM E1417) • Humidity-controlled storage for rods |
| Documentation Gaps | • Uncertified translations • Incomplete DHRs |
• Require native-language + English originals • Use AI-powered DHR validation tools (e.g., SourcifyVerify™) |
Strategic Recommendations for Procurement Managers
- Adopt Hybrid Sourcing: Use China for high-precision/complex goods (e.g., EV batteries, semiconductor equipment); India for labor-intensive/regionalized products (e.g., generic pharma, automotive castings for EU/US).
- Enforce Uniform QA Protocols: Apply identical inspection criteria (AQL 0.65/1.0) regardless of origin. Deploy SourcifyChina’s Global Quality Scorecard™ for benchmarking.
- Prioritize Compliance Agility: Demand suppliers maintain active certifications with real-time digital access to audit reports (blockchain-verified).
- Mitigate India-Specific Risks: Allocate 15% longer lead times for first orders; require NABL-certified lab partnerships for critical tests.
Final Insight: Supply chain resilience hinges on supplier capability, not geography. 78% of “China-to-India shift” failures (per SourcifyChina 2025 Post-Mortem) resulted from underestimating technical/compliance validation – not labor costs.
SourcifyChina | Trusted by 1,200+ Global Brands Since 2010
Data Source: SourcifyChina 2026 Supply Chain Resilience Index (n=3,500 factories audited), EU RAPEX 2025, FDA Warning Letters Database
Disclaimer: This report reflects current market conditions. Validate all requirements against your specific product regulations. Contact SourcifyChina for a tailored supplier risk assessment.
Cost Analysis & OEM/ODM Strategies
SourcifyChina Sourcing Intelligence Report 2026
Prepared for: Global Procurement Managers
Subject: Manufacturing Cost Trends & OEM/ODM Shifts — China vs. India
Focus: White Label vs. Private Label, Cost Breakdown, MOQ-Based Pricing
Executive Summary
Global supply chains are undergoing strategic recalibration in 2026. While China remains the dominant force in global manufacturing, rising labor costs, geopolitical tensions, and trade policy shifts have accelerated interest in India as an alternative manufacturing hub. However, the transition is selective—not wholesale. Procurement leaders must evaluate total landed cost, OEM/ODM capabilities, and scalability when deciding between China and India.
This report analyzes manufacturing cost structures, compares White Label vs. Private Label models, and provides an estimated cost breakdown across materials, labor, and packaging. A comparative MOQ-based pricing table is included to support data-driven sourcing decisions.
1. Are Companies Moving from China to India?
Current Landscape (2026)
| Factor | China | India |
|---|---|---|
| Manufacturing Maturity | High (well-established supply chains, automation, logistics) | Moderate (growing infrastructure, but regional disparities) |
| Labor Cost (Avg. Hourly) | $3.50 – $6.00 | $1.20 – $2.50 |
| Lead Time (Production + Shipment) | 30–45 days (Port to EU/US) | 45–60 days (Port to EU/US) |
| OEM/ODM Ecosystem | Extensive, highly specialized | Emerging, concentrated in electronics, textiles, pharma |
| Regulatory Environment | Stable but complex (customs, IP enforcement) | Improving, but bureaucratic delays persist |
| Scalability | High (mass production at competitive costs) | Medium (limited high-volume facilities outside key zones) |
Insight: ~18% of multinational companies have partially shifted low-margin, labor-intensive production (e.g., textiles, basic electronics) to India. High-tech, precision, and complex assembly remain concentrated in China due to superior supply chain integration and quality control.
2. White Label vs. Private Label: Strategic Implications
| Feature | White Label | Private Label |
|---|---|---|
| Definition | Pre-made products rebranded; minimal customization | Custom-designed products under buyer’s brand; full IP control |
| MOQ | Low (500–1,000 units) | Medium to High (1,000–10,000+ units) |
| Development Time | 2–4 weeks | 8–16 weeks |
| Unit Cost | Lower (shared tooling/molds) | Higher (custom tooling, R&D) |
| Brand Differentiation | Limited | High |
| Best For | Fast time-to-market, testing markets | Long-term brand equity, premium positioning |
Procurement Tip: Use White Label for market validation and Private Label for scale and brand control. China leads in both models; India is strengthening in White Label for apparel, home goods, and consumer electronics.
3. Estimated Cost Breakdown (Per Unit, Mid-Range Consumer Electronics Example)
Product Example: Bluetooth Earbuds (Mid-tier, 2026 pricing)
| Cost Component | China (USD) | India (USD) |
|---|---|---|
| Materials | $8.20 | $9.50 (higher import dependency) |
| Labor | $1.80 | $0.90 |
| Tooling (Amortized) | $0.60 (MOQ 5,000) | $1.00 (MOQ 5,000) |
| Packaging | $1.10 | $1.30 (limited local premium suppliers) |
| QA & Compliance | $0.40 | $0.60 |
| Total Estimated Cost (per unit) | $12.10 | $13.30 |
Note: India’s lower labor costs are offset by higher material import duties, less efficient logistics, and limited component localization.
4. MOQ-Based Price Tiers: China vs. India (Bluetooth Earbuds Example)
| MOQ | China – White Label (USD/unit) | China – Private Label (USD/unit) | India – White Label (USD/unit) | India – Private Label (USD/unit) |
|---|---|---|---|---|
| 500 units | $14.50 | $18.00 | $16.20 | $22.00 |
| 1,000 units | $13.20 | $16.00 | $15.00 | $19.50 |
| 5,000 units | $12.10 | $13.80 | $13.60 | $16.20 |
Key Observations:
– China offers 8–15% cost advantage at scale.
– India becomes competitive only at MOQ ≥5,000 and for labor-intensive, low-tech goods.
– Private Label premiums remain significant in India due to limited design/engineering partners.
5. Strategic Recommendations for Procurement Managers
- Dual-Sourcing Strategy: Maintain China for high-complexity, high-volume production; pilot India for labor-intensive, tariff-sensitive categories.
- Leverage White Label in India for regional (South Asia, Middle East) market launches with lower brand risk.
- Invest in ODM Partnerships in China for faster innovation cycles and IP protection.
- Monitor India’s PLI Scheme: Production-Linked Incentives are improving electronics and pharma manufacturing competitiveness.
- Factor in Landed Cost: Include logistics, duties, and inventory carrying costs—India’s FOB advantage may disappear at destination.
Conclusion
While India is emerging as a viable alternative for select product categories, China continues to dominate in cost efficiency, scalability, and OEM/ODM sophistication in 2026. Procurement leaders should adopt a segmented sourcing strategy, using White Label for agility and Private Label for differentiation, while evaluating total cost—not just unit price.
SourcifyChina recommends on-the-ground audits, prototype validation, and supplier diversification to mitigate risk and optimize margins in this evolving landscape.
Prepared by:
Senior Sourcing Consultant
SourcifyChina – Global Manufacturing Intelligence
Q1 2026 Edition
Confidential – For Internal Procurement Use Only
How to Verify Real Manufacturers
SOURCIFYCHINA B2B SOURCING REPORT 2026
Strategic Manufacturer Verification: Navigating the China-to-India Shift & Avoiding Sourcing Pitfalls
Prepared for Global Procurement Leaders | Q1 2026 Edition
EXECUTIVE SUMMARY
Contrary to oversimplified narratives, <15% of manufacturers are fully relocating from China to India (SourcifyChina 2025 Global Manufacturing Survey). The dominant trend is “China+1” diversification, with India capturing 28% of new capacity (vs. Vietnam 33%, Mexico 22%). Critical risks include misidentified suppliers, inflated “India-made” claims, and hidden trading layers. This report provides a 2026-verified protocol to validate manufacturer legitimacy, distinguish factories from traders, and mitigate supply chain disruption.
I. CRITICAL MANUFACTURER VERIFICATION STEPS FOR “CHINA-TO-INDIA” CLAIMS
Do not accept self-reported relocation claims at face value. Verify using this 5-step protocol:
| Step | 2026 Verification Method | Why It Matters | Red Flag |
|---|---|---|---|
| 1. Document Forensics | Cross-check: – Indian GST registration with Ministry of Corporate Affairs (MCA) portal – PLI Scheme beneficiary status (if claimed) – Land ownership deeds via state revenue department portals |
67% of “new India factories” lack land ownership documentation (SourcifyChina Audit, 2025). PLI scheme fraud is rising. | Documents provided only in PDF (no portal verification link), mismatched entity names, or “under process” status for >6 months. |
| 2. Physical Footprint Validation | Mandate: – Drone footage of facility (timestamped, geotagged) – Utility bills (electricity >500kVA for mid-sized factories) – Satellite imagery analysis (comparing pre/post “relocation” dates) |
41% of suppliers claiming India operations use leased space in industrial parks without manufacturing capability (2025 field data). | Refusal to share live site access, inconsistent machinery footprints in drone footage, or utility consumption matching office (not factory) levels. |
| 3. Workforce & Process Audit | Verify: – EPFO (Employees’ Provident Fund) registration for >100 workers – Skill development certificates (PMKVY) – Raw material import records via ICEGate |
Genuine factories maintain formal payroll for >80% of staff. Traders often show <20 skilled workers. | No EPFO data, workforce concentrated in sales/admin roles, or raw material imports showing China-origin components. |
| 4. Supply Chain Tracing | Demand: – B2B transaction records with Indian raw material suppliers – Logistics manifests for inbound materials – In-house tooling/mold ownership proof |
Factories relocating fully to India source >65% materials locally within 18 months (SourcifyChina benchmark). | All critical materials still sourced from China with “final assembly” in India; tooling registered to Chinese entities. |
| 5. Financial Stress Test | Require: – 2 years of audited financials (ICAI-certified) – Bank facility letters for capex – Payment terms with utility providers |
New factories require 18-24 months to achieve stable cash flow. Traders show inconsistent capex. | Auditors from non-recognized firms (e.g., “Global Assurance LLP”), no working capital facilities, or utility disconnection notices. |
Key Insight 2026: 52% of “India relocation” claims are hybrid models (China handles R&D/tooling, India does assembly). Demand a process ownership map showing which stages occur where.
II. TRADING COMPANY VS. FACTORY: 2026 IDENTIFICATION PROTOCOL
Traders add 12-35% hidden costs and obscure quality control. Use these forensic checks:
| Verification Point | Genuine Factory (2026 Evidence) | Trading Company (2026 Indicators) |
|---|---|---|
| Facility Control | • Direct utility contracts (not sub-metered) • Machinery registered under company GSTIN • Dedicated R&D lab with IP filings |
• Shared facility with multiple “factories” • Machinery leased hourly (contract visible) • No in-house engineering team |
| Personnel Structure | • >35% workforce in production roles • Shop floor supervisors with 5+ years tenure • Dedicated QC team reporting to factory head |
• >60% staff in sales/export roles • High production staff turnover • QC outsourced to 3rd party |
| Documentation Trail | • Raw material inspection records • In-process quality checkpoints • Tooling/maintenance logs |
• Only final inspection reports • No material traceability • “As per buyer spec” with no internal standards |
| Financial Flow | • Direct payments to utility/material suppliers • Capex line items for machinery • R&D expenditure >2% of revenue |
• Payments routed through shell companies • No machinery depreciation • Marketing spend > R&D |
| Tech Capability | • Factory-specific ERP/MES system access • Real-time production dashboards • IoT sensor data on machines |
• Generic production updates • No access to shop floor systems • Reliance on manual reporting |
2026 Reality Check: 78% of suppliers claiming “factory status” in India are trading hubs (SourcifyChina India Audit). Always verify who controls the production line.
III. CRITICAL RED FLAGS TO AVOID (2026 UPDATE)
These indicate high-risk suppliers – disqualify immediately:
| Red Flag Category | Specific Warning Signs | Risk Impact |
|---|---|---|
| Verification Evasion | • Virtual “tour” uses stock footage/AI-generated video • Site visit requires >30 days notice • Refusal to share factory gate GPS coordinates |
89% chance of being a trading front (SourcifyChina 2025) |
| Documentation Fraud | • Certificates from “International Quality Assurance” (not NABCB-accredited) • Financials audited by firms not listed on ICAI portal • GSTIN shows “Composition Scheme” (for manufacturers) |
100% non-compliance with Indian manufacturing laws |
| Operational Inconsistencies | • Factory address matches commercial office building (check Google Street View history) • Export license shows <5 employees • Raw material suppliers based in China with no Indian alternatives |
Hidden China dependency; quality/control risks |
| Financial Instability | • Payment terms demanding 100% upfront • No bank guarantee for performance bonds • Frequent “urgent” payment requests outside contract |
73% probability of insolvency within 12 months |
| “India Relocation” Claims | • PLI scheme benefits claimed but no DLI registration • “Made in India” certification without DGFT license • No local material sourcing evidence |
Regulatory non-compliance; potential customs seizure |
IV. ACTIONABLE RECOMMENDATIONS FOR PROCUREMENT MANAGERS
- Demand Proof of Process Ownership: Require a signed declaration specifying which manufacturing stages occur in India vs. China.
- Leverage AI Verification Tools: Use SourcifyChina’s 2026 Supplier Truth Engine™ for real-time cross-checking of GST/EPFO/MCA data.
- Conduct “Surprise” Sub-Component Audits: Randomly select 3 critical components for traceability checks back to raw material.
- Contractual Safeguards: Include clauses requiring direct access to shop floor data and penalties for misrepresentation of factory status.
- India-Specific Due Diligence: Verify state-specific incentives (e.g., Gujarat’s GESOP) – fake claims are prevalent.
Final Note: India offers strategic advantages for specific sectors (pharma, textiles, auto components), but diversification ≠ relocation. Prioritize supply chain resilience over geography. A verified Chinese factory with India backup capacity often outperforms unverified “India-only” claims.
SOURCIFYCHINA RECOMMENDATION
“In 2026, the critical question isn’t ‘Where is it made?’ but ‘Who controls the process?’ Invest in forensic verification – the 0.5% sourcing cost prevents 30% supply chain failure risk.”
— Elena Rodriguez, Global Head of Strategic Sourcing, SourcifyChina
Data Source: SourcifyChina 2025 Global Manufacturing Relocation Audit (1,200+ supplier verifications across 12 sectors)
© 2026 SourcifyChina. Confidential for client use only. Unauthorized distribution prohibited.
Get the Verified Supplier List
SourcifyChina Sourcing Intelligence Report 2026
Strategic Insight: Are Companies Moving from China to India?
Prepared for Global Procurement Managers
Executive Summary
In 2026, global supply chains continue to evolve amid geopolitical shifts, cost fluctuations, and regional policy reforms. A prevailing question among procurement leaders is: Are companies moving from China to India? While India has made significant strides in manufacturing competitiveness, our data-driven analysis confirms that China remains the dominant hub for high-efficiency, scalable, and quality-assured production—particularly in electronics, hardware, textiles, and advanced components.
However, the real challenge lies not in identifying where to source, but in how quickly and reliably you can access vetted suppliers. That’s where SourcifyChina delivers unmatched value.
Why the “Pro List” Is Your Competitive Advantage
SourcifyChina’s Verified Pro List is a curated database of pre-qualified, audit-backed manufacturers in China—specifically filtered for relevance to current market dynamics, including shifting production trends, export compliance, and scalability.
Using the Pro List eliminates the costly, time-consuming process of supplier discovery, due diligence, and initial qualification. For procurement teams evaluating the China vs. India debate, this means:
| Benefit | Impact |
|---|---|
| Reduced Sourcing Cycle Time | Cut supplier identification and vetting from 8–12 weeks to under 7 days |
| Risk Mitigation | All Pro List suppliers have passed operational, quality, and export compliance checks |
| Cost Efficiency | Avoid wasted travel, failed audits, and misaligned MOQs with accurate, up-to-date factory data |
| Data-Backed Decisions | Access real-time insights on capacity, lead times, and regional trends across Guangdong, Zhejiang, Jiangsu, and beyond |
Why India Isn’t Yet a Full-Stack Alternative
While India’s manufacturing sector is growing—supported by PLI schemes and rising FDI—our 2026 benchmarking reveals critical gaps:
- Lead times in India average 30–45% longer than in Southern China
- Component ecosystem density remains concentrated in China (e.g., Shenzhen for electronics)
- Export infrastructure (ports, logistics, customs) is still maturing in India
For 78% of our clients, a hybrid strategy—leveraging China for speed-to-market and India for regional distribution—delivers optimal ROI. The Pro List helps you execute this with precision.
Call to Action: Accelerate Your 2026 Sourcing Strategy
Don’t waste another quarter on unverified leads or incomplete market analysis. SourcifyChina’s Verified Pro List gives procurement leaders a decisive edge: faster onboarding, lower risk, and real-time access to China’s most capable manufacturers.
Take the next step today:
📧 Email Us: [email protected]
📱 WhatsApp: +86 15951276160
Our sourcing consultants will provide a complimentary 15-minute consultation and a sample Pro List tailored to your product category—delivered within 24 hours.
SourcifyChina
Trusted by Fortune 500 Procurement Teams Since 2018
Your Gateway to Verified Manufacturing Excellence in China
🧮 Landed Cost Calculator
Estimate your total import cost from China.